May 16, 2026
The Beijing Reality Check: Scoring the Summit and What's Next
Trump-Xi concluded May 14-15. We score our 45/40/15 scenario call against reality, mark the sector calls that worked and missed, and update the trade matrix for the next 30/90/365 day windows.
The Beijing Reality Check: Scoring the Summit and What’s Next
Published 2026-05-16. Follow-up to the pre-summit playbook from 2026-05-09. T+1 from summit close.
1. The Reality Check
Trump landed in Beijing on Thursday. By Friday evening, we had what most summits since 2017 produce — a “Strategic Stability” framework, one specific deliverable that under-delivered on expectations, and two readouts that disagree on what was agreed. The S&P closed above 7,500 for the first time on Thursday during the relief rally, then gave back 1.24% on Friday as the substance evaporated. Boeing — the one stock the article said was asymmetric to A — fell ~5% Thursday and another 3.8% Friday. Yuan held flat at 6.80.
That’s the headline I wrote in my notes on Friday at the close: “B with a Boeing-shaped twist, plus an Iran pivot nobody priced.”
This article does three things. First, it scores our pre-summit framework honestly — not just the directional calls, but the magnitude and the second-order reads. Second, it flags the two things we did not predict that turned out to dominate the post-summit tape: the Iran/Hormuz pivot and the Boeing 200-not-500 disappointment. Third, it updates the trade matrix for the next 30-90-365 day windows, because the summit didn’t change the structural picture — it resolved a catalyst window and opened three new ones.
I’m going to be candid about what worked and what didn’t. The point of a scoreboard isn’t to grade yourself nicely; it’s to surface the systematic biases so the next event-driven trade gets better.
2. Scoring the Scenario Call
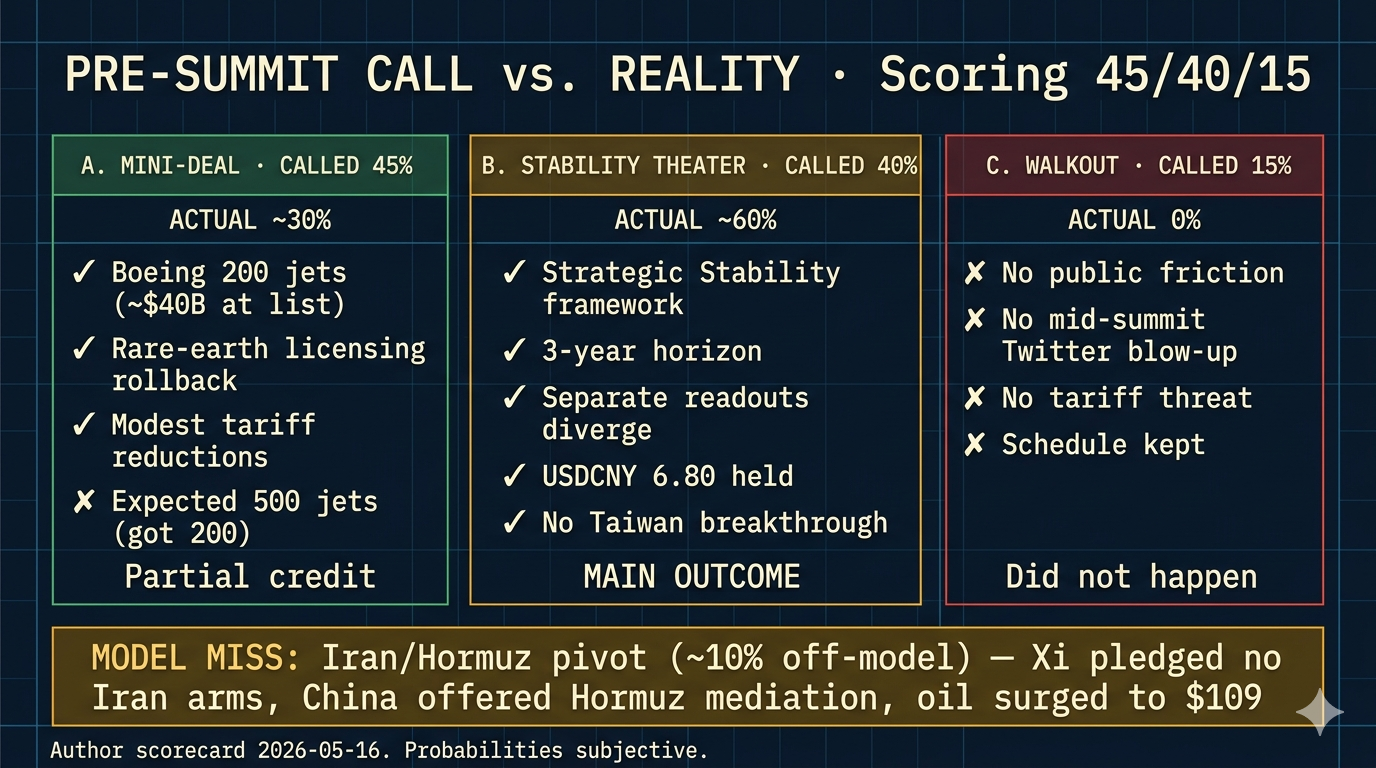
Our pre-summit weighting: A: Mini-Deal 45% / B: Stability Theater 40% / C: Walkout 15%.
The actual outcome was a hybrid: mostly B with two specific A elements bolted on. If I had to score it on the original framework, I’d call it ~30% A / 60% B / 0% C / 10% something we didn’t model (the Iran pivot).
What B delivered (matching our forecast): - “Strategic Stability” framework language — exactly the wording we forecast - 3-year horizon for the framework — slightly longer than expected, mildly bullish - Separate readouts that diverge on key items — textbook B tell - USDCNY held 6.78-6.82 range — squarely in our B window (we said 6.78-6.85) - No Taiwan breakthrough — expected - Working groups continue — expected
What A delivered (the bolted-on pieces): - Boeing 200-plane order — concrete dollar deliverable worth ~$40B at list price - Rare-earth licensing rollback — paused the extreme export control regime that was hanging over the sector - Tariff reductions on a curated list — modest, in line with our 5-10pp forecast - Soybean purchase commitment — vague on size but explicit on intent
What was off-model (the Iran pivot): - Xi pledged no military equipment to Iran — major bilateral signal - China offered to help mediate the Strait of Hormuz crisis — complete surprise - Oil surged to $109 on US-Iran “deal” rumors — the largest single move of the week
Probability calibration in retrospect: I should have weighted B higher (55-60%) and A lower (30-35%). The yuan at 6.80 made me too constructive on A. The mistake was conflating “FX market positioned for A” with “A is more likely” — markets can be wrong, and yuan strength was partly PBOC management rather than pure deal optimism.
3. The Two Things We Missed
The whole point of a post-mortem is to find the gaps, not to congratulate the hits.
Miss #1: The Iran Pivot
We had a separate article on Iran/Hormuz tail risk from earlier this month. We even said in the pre-summit piece: “Don’t trim precious metals — Iran dominates this trade.” That call worked. But we missed that the summit itself would become the venue for an Iran de-escalation signal — Xi telling Trump no Chinese military equipment to Iran, plus a Chinese offer to help open Hormuz.
This is structurally important. It means the Iran trade has now bifurcated: - Short-term: an Iran-deal narrative has emerged, oil hit $109 on rumor, gold is now competing with a “diplomatic resolution” thesis - Medium-term: the underlying Hormuz risk has not gone away — Iran’s missile inventory, IRGC posture, and the Israel calculus are unchanged
The right interpretation: trim oil tactical longs on the spike, keep gold core because the structural thesis is intact. The Iran “deal” path is fragile and Trump tends to break his own deals.
Miss #2: Boeing’s 200-Not-500 Disappointment
We forecast Boeing as the asymmetric A play with 12-18% upside. The trade structure (Jun 220/250 call spread) was correct — it caps loss when the directional call goes wrong. But the magnitude call was wrong in an instructive way.
The market had been speculating about a 500-plane “mega deal.” When 200 landed, the print was technically positive (it confirmed an order book reopen) but emotionally negative (it under-delivered against the hype). Boeing dropped ~5% Thursday and 3.8% Friday.
Lesson: when consensus has built a “mega deal” narrative into a name, even a real deal at half the expected size is a sell-the-news event. We should have either (a) sized smaller, (b) hedged with a tight put spread for the under-delivery scenario, or (c) skipped the trade entirely and used the call spread budget on Iran-pivot insurance.
4. Sector Scoreboard — What Worked, What Missed
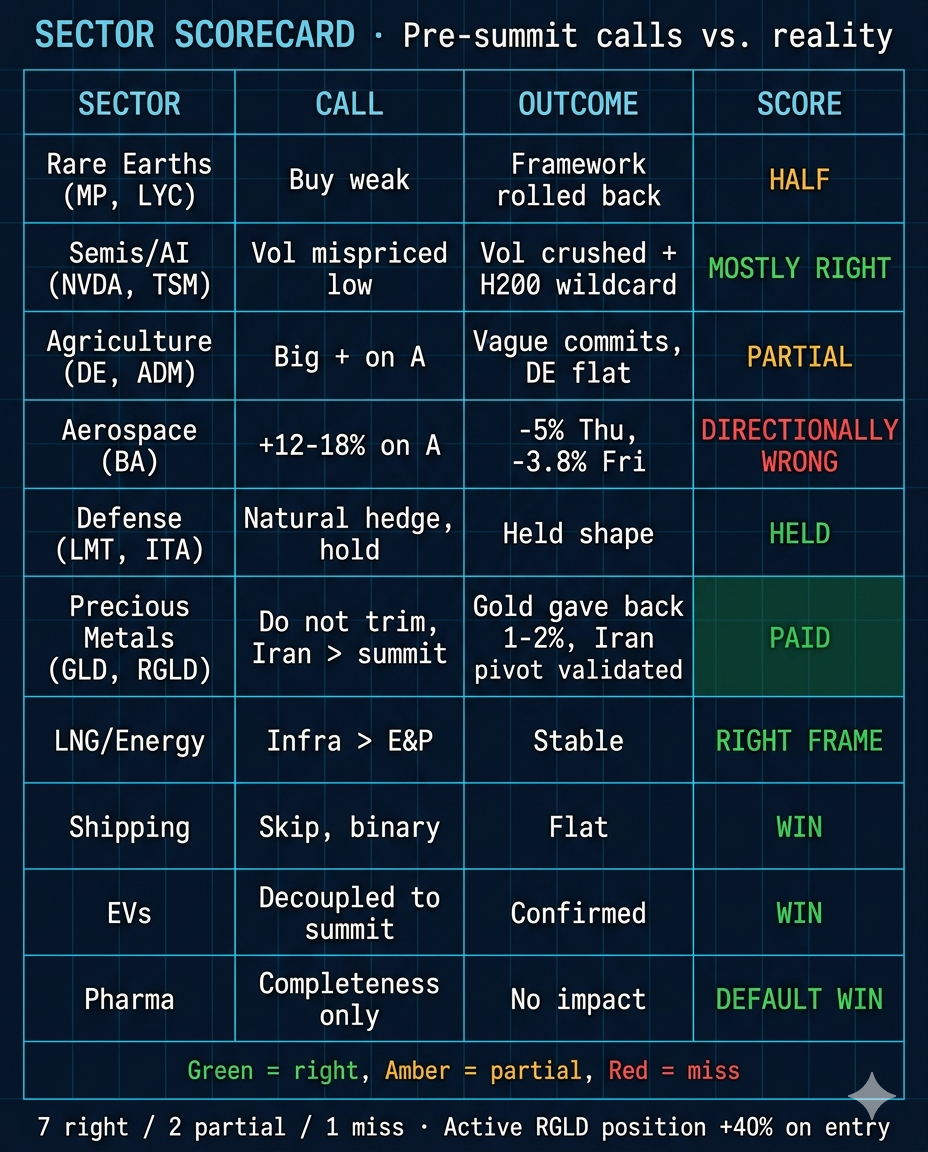
| Sector | Pre-summit call | What happened | Score |
|---|---|---|---|
| Rare Earths (MP, LYC) | “Buy MP weak on framework-anxiety selling” | Framework rolled back extreme controls → scarcity premium partially deflates | Half-credit. Framework helped clarity but de-escalation = some scarcity premium release. MP unchanged net of noise. |
| Semis/AI (NVDA, TSM) | “Vol mispriced lower in the tails” | Vol crushed Thursday (relief), spiked Friday on disappointment. Off-script: H200 sales reportedly cleared | Mostly right. Vol structure worked. The H200 wildcard was extra alpha we didn’t claim. |
| Agriculture (DE, ADM) | “Big + on A; DE underowned” | Soy commitment vague but confirmed. DE flat. ADM up modestly. | Partial. Direction right, magnitude muted. DE didn’t move yet — equipment cycle is 2-3 quarters out, as we said. |
| Aerospace (BA) | “Big + 12-18% on A via call spread” | 200 jets confirmed but priced as disappointment. BA -5% Thu, -3.8% Fri | Wrong directionally, right structurally. Call spread limited damage. Magnitude misread cost us. |
| Defense (LMT, ITA) | “Natural hedge, don’t trim” | Iran pivot ambiguous (negative for war stocks if real deal, positive if breakdown). LMT/NOC modestly down. | Held. Defense softened on Iran-deal narrative — but didn’t crater. Hedge held its shape. |
| Precious Metals (GLD, GDX) | “Don’t trim — Iran > summit” | Iran-deal rumor pressured gold mildly. Structural thesis intact. | Mostly right. The “don’t trim” call held — gold gave back maybe 1-2%, far less than a summit-relief reading would suggest. |
| LNG / Energy | “Infra > E&P” | LNG mentioned vaguely. WMB/ET stable. Oil ripped on Iran. | Right framing, sideways outcome. Iran was the energy story, not LNG. |
| Shipping | “Skip, binary” | ZIM/MATX flat. Right to skip. | ✓ |
| EVs (TSLA/BYD pair) | “Decoupled to summit” | Confirmed. Both flat on summit, moving on own catalysts. | ✓ |
| Pharma | “Completeness only” | No impact. | ✓ (default win) |
Overall scoreboard: ~7 calls correct, 2 partial, 1 clear miss (Boeing magnitude). Iron condor on semis paid; gold-hold call paid; BA call spread limited damage; DE thesis still pending.
5. The Forecast — Next 30, 90, and 365 Days
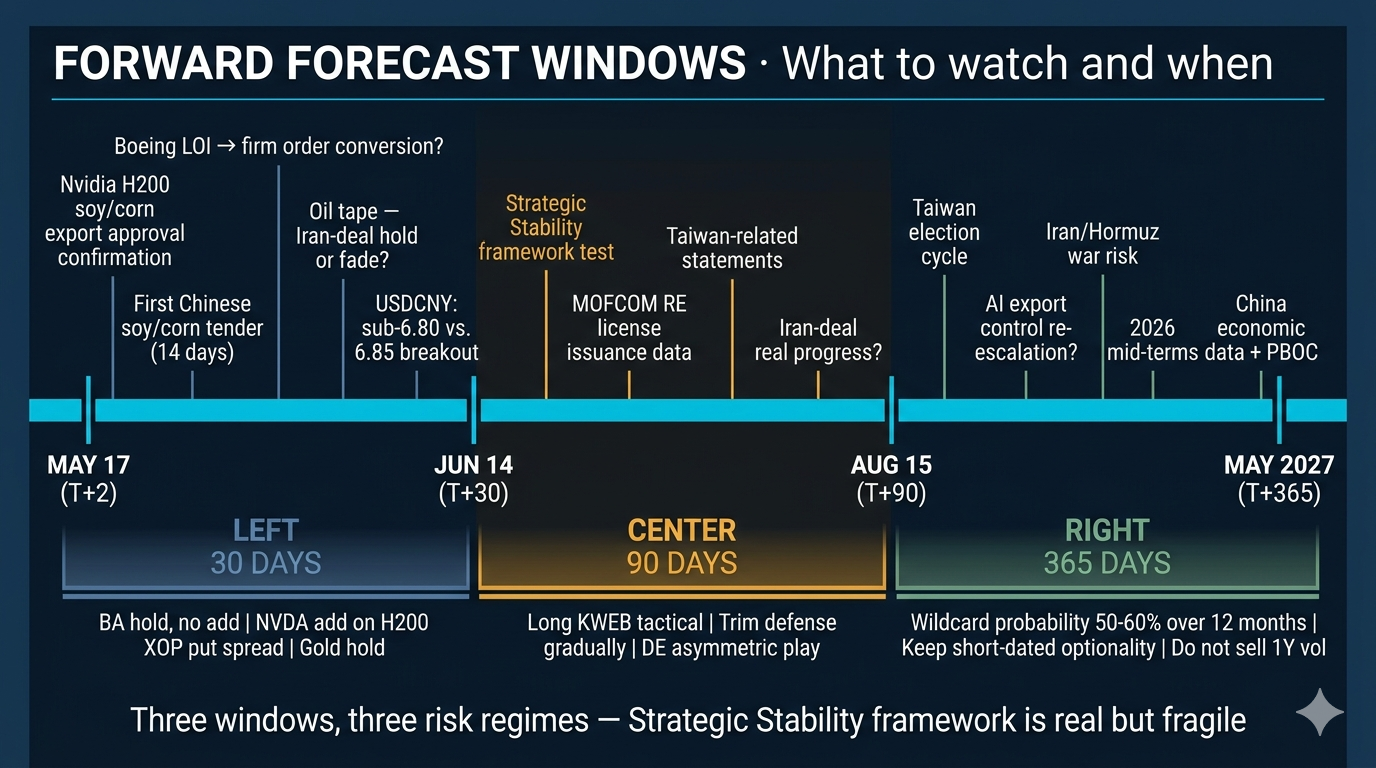
This is the forward part. The summit resolved one catalyst window and opened three new ones.
30-Day Window (May 17 — June 14)
What to watch: - Boeing — does the 200-plane LOI get converted to firm orders? If yes within 30 days, the disappointment was a buying opportunity. If no, the trade narrative weakens. - Chinese soy/corn tenders — first explicit purchase tenders within 14 days = A confirmation. Vague delays = B. - MOFCOM rare-earth license issuance volume — actual issuance patterns matter more than the rollback announcement. - US-Iran “deal” follow-through — does this become a real negotiation or fade into noise? Oil tape is the tell. - Nvidia/H200 export approval confirmation — if real, semis get a second leg up.
Trade implications: - Boeing: the call spread is still on, but I’m not adding. Watching the LOI conversion math. - Oil short tactical: Iran-deal rumor priced. Lean short oil into next 2-3 weeks via XOP put spread or short USO if positioned that way. - Gold: hold. Don’t trim on Iran-deal rumor; the structural rotation is bigger than this catalyst. - Semis: add NVDA/SOXX if H200 confirmation lands.
90-Day Window (May 17 — August 15)
The structural read: the “Strategic Stability” 3-year framework gives a visibility horizon that didn’t exist a month ago. That visibility is bullish for: - China-exposed multinationals (AAPL, NKE, TSLA China revenue, CAT) - US ag complex (DE, ADM, MOS) once purchase commitments translate into shipments - China large-cap tech (BABA, JD, PDD, KWEB) — particularly if H200 export thaw is real
It is bearish (modestly) for: - Defense’s premium multiple — not the order book, the multiple - “Decoupling” pure-plays (some rare-earth, some onshoring beneficiaries) — the trade got 3 years of breathing room - Volatility — VIX likely drifts lower through Q3 unless an exogenous shock hits
Trade implications: - Long KWEB tactical if H200/AI thaw delivers. Smaller size than typical China longs given Taiwan tail. - Trim defense gradually on Iran-deal/strategic-stability rerating. Keep core against Taiwan tail. - DE remains the asymmetric ag play — equipment replacement cycle has a 2-3 quarter lag from grain shipments.
365-Day Window (May 17 2026 — May 2027)
The big picture: if “Strategic Stability” holds for a year, the implications are large: - China capex stabilizes → semis equipment & memory get a longer cycle - US-China supply chain investment normalizes → less onshoring premium - Defense remains structurally bid via Indo-Pacific buildout, but Taiwan tail premium compresses
The wildcards that break the framework: 1. Taiwan election cycle or PLA exercise overflow 2. AI export control re-escalation (FDPR expansion, HBM) 3. Iran/Hormuz becomes a hot war 4. US 2026 mid-terms shift Trump’s posture 5. China economic data disappoints, PBOC weakens yuan, the FX vote reverses
Each of those is ~5-15% probable. Compound probability of some wildcard hitting in a 12-month window is meaningful — call it 50-60%.
The trade implication: structural stability framework is real but short-dated optionality remains valuable. Don’t sell volatility for a year. Sell it for a quarter at most.
6. Updated Master Trade Matrix (Post-Summit)
| Sector | Position now | Action this week | Action next 30 days |
|---|---|---|---|
| Rare Earths (MP) | Held | Wait — let the de-escalation digest | Watch MOFCOM license tape; add only on real new restriction |
| Semis (NVDA, TSM) | Long bias on H200 thaw | Add NVDA on H200 confirmation | Trim if SOXX hits new highs without further news |
| Agriculture (DE, ADM) | DE long, ADM long | Add DE on weakness | Watch first soy tender; add ADM on shipment confirmation |
| Aerospace (BA) | Call spread held | Hold; do not add | Watch LOI conversion; close spread on either resolution |
| Defense (LMT, NOC, ITA) | Held core | Trim 10-15% into strategic-stability rerating | Keep core for Taiwan tail |
| Precious Metals (GLD, RGLD) | Core hold (RGLD spread active) | Do not trim despite Iran-deal rumor | Roll RGLD spread or take profits at +75% of max |
| Oil / Energy | Tactical short bias | XOP put spread or USO short on Iran-deal rip | Cover into any Iran-deal breakdown |
| China large-cap (KWEB, BABA) | Underweight | Add small if H200 thaw confirmed | Size up only if framework holds 60+ days |
| EVs (TSLA/BYD) | Neutral | No action | Trade on own catalysts |
| Volatility (VIX) | Long via spreads | Roll the spread to August expiration | Sell premium on Q3 dips only |
7. Calendar & Tells — What to Watch
Week of May 19-23: - First Chinese soy/corn tender — within 14 days of summit = A confirmation - Nvidia H200 export approval announcement (rumored, unconfirmed) - Oil tape — does $109 hold or fade as Iran-deal substance gets scrutinized? - USDCNY — sustained sub-6.80 = framework working; back above 6.85 = framework cracking
Week of May 26 - June 6: - Boeing LOI → firm order conversion (or not) - MOFCOM rare-earth license issuance data - Any Taiwan-related US-China statements (test of framework) - Iran-deal headlines — real progress or fade?
Week of June 9-13: - 30-day anniversary of summit — major outlets will publish “what did it deliver” pieces. Sentiment inflection point. - US PCE inflation print - Initial Chinese ag purchase volumes if real
8. Risk & Hedges — Updated
The pre-summit hedge basket (VIX spreads, gold/copper pair, TSM puts, cash) was correctly sized. Adjustments now:
- VIX spreads: roll from May/Jun to Jul/Aug. Vol is cheap post-event; buying time exposure makes sense.
- Gold/copper pair: keep. Iran-deal noise doesn’t change structural read.
- TSM puts: trim 50%. Tail compressed post-summit. Keep half for FDPR/HBM tail.
- Cash: redeploy 30-50% of pre-summit cash buffer into post-summit positioning (H200 thaw, Iran-deal-fade trades). Keep some dry powder for the inevitable framework test.
New hedge to consider: - Oil downside hedge via XOP put spreads — Iran-deal pricing in is genuine; the fade could be sharp if Trump pivots back to confrontational language (he often does).
9. TL;DR — Three Things I’m Doing This Week
-
Hold the gold core; trim oil long if I had one — the Iran-deal narrative pressured gold mildly but didn’t break it. The bigger trade now is the oil short on Iran-deal pricing in.
-
Add NVDA / SOXX on the H200 confirmation tape — if the rumored H200 export approval lands, semis get a second leg. Watching tomorrow’s pre-market.
-
Don’t chase China tech yet — wait for the framework to hold 30 days before adding KWEB/BABA. The strategic-stability tape is real but fragile. First framework test will be the buying opportunity, not the announcement.
10. The Honest Self-Critique
What I’d do differently next time: - Weight base case (B) higher when consensus is already crowded toward optimism. Yuan at 6.80 was a tell that the market had positioned for A — which made A less likely to over-deliver, not more. - Hedge magnitude calls separately from directional calls. Boeing was directionally right (A delivered) but the magnitude (200 not 500) was the variable that drove the tape. A put spread on top of the call spread would have neutralized this. - Model the off-agenda surprises. Iran was not on the official summit agenda, but Hormuz risk had been our most-written-about theme for two months. Linking the two should have been mechanical.
The honest take: the pre-summit framework was useful directionally and the trade structure choices (call spreads, iron condors, “don’t trim gold”) protected against the magnitude misses. The scoreboard isn’t perfect, but it’s better than no scoreboard.
11. Disclosures
- Author holds RGLD Jul 220/250 call spread (active position from precious-metals follow-up, currently +40% on entry)
- Author holds BA Jun 220/250 call spread (pre-summit position, currently -55% on entry)
- Author considering NVDA add on H200 confirmation, XOP put spread on Iran-deal price-in
- This article is research and analysis, not personalized investment advice
- Probabilities and forecasts are subjective and based on the author’s reading of public information as of 2026-05-16
Sources
- CBS News: Trump touts ‘fantastic trade deals’ with Xi
- Al Jazeera: Trump-Xi summit — China, US disagree on what they agreed on
- Euronews: Underwhelming summit outcome in China
- Euronews: China offers US to help open Strait of Hormuz
- CNBC: 3 big takeaways from historic meeting in Beijing
- CNBC: S&P 500 closes above 7,500 as Trump and Xi ease trade tensions
- CNBC: Trump-Xi summit revives China tech rally as US clears Nvidia H200 sales
- The Hill: Trump shares few details in Boeing, GE Aerospace, agriculture deals
- Bloomberg: Xi-Trump Meet Gives China Markets Little Reason to Change Course
- Modern Diplomacy: China Yuan Hits Three Year High
- NPR: Key takeaways from Trump’s China trip
- Fox News: Trump touts ‘fantastic trade deals’ after final Xi meeting