Mar 14, 2026
$NVDA Q4 FY2026 Deep Dive: The Market Is Pricing 'Compute = Revenue' — But Regime-Change Risk Is Underpriced
NVIDIA Q4 FY2026 earnings deep dive: $68.1B revenue (+73% YoY), Blackwell supercycle, but at $178 the implied IRR is only 13% — below our 15% hurdle. Wait for $155-165 pullback.
$NVDA Q4 FY2026 Deep Dive
The Market Is Pricing “Compute = Revenue” — But Regime-Change Risk Is Severely Underpriced
Executive Summary
NVIDIA reported its strongest quarter ever: $68.1B revenue (+73% YoY), Q1 FY27 guidance of $78B (vs $72B consensus), and $90B in free cash flow for the full year. The stock dropped 5.5% on earnings day, wiping $260B in market cap — a “good news is priced in” signal. Growth is fully priced; the market is beginning to question sustainability.
Bottom line: Great company, insufficient risk/reward at $178. - Forward P/E: ~21.5x — looks cheap, but embeds 50%+ growth assumptions - Probability-weighted 12M target: $183 — implied IRR ~13% (below our 15% threshold) - Action Price: $157 for first tranche, $140 for adding
Key Forces
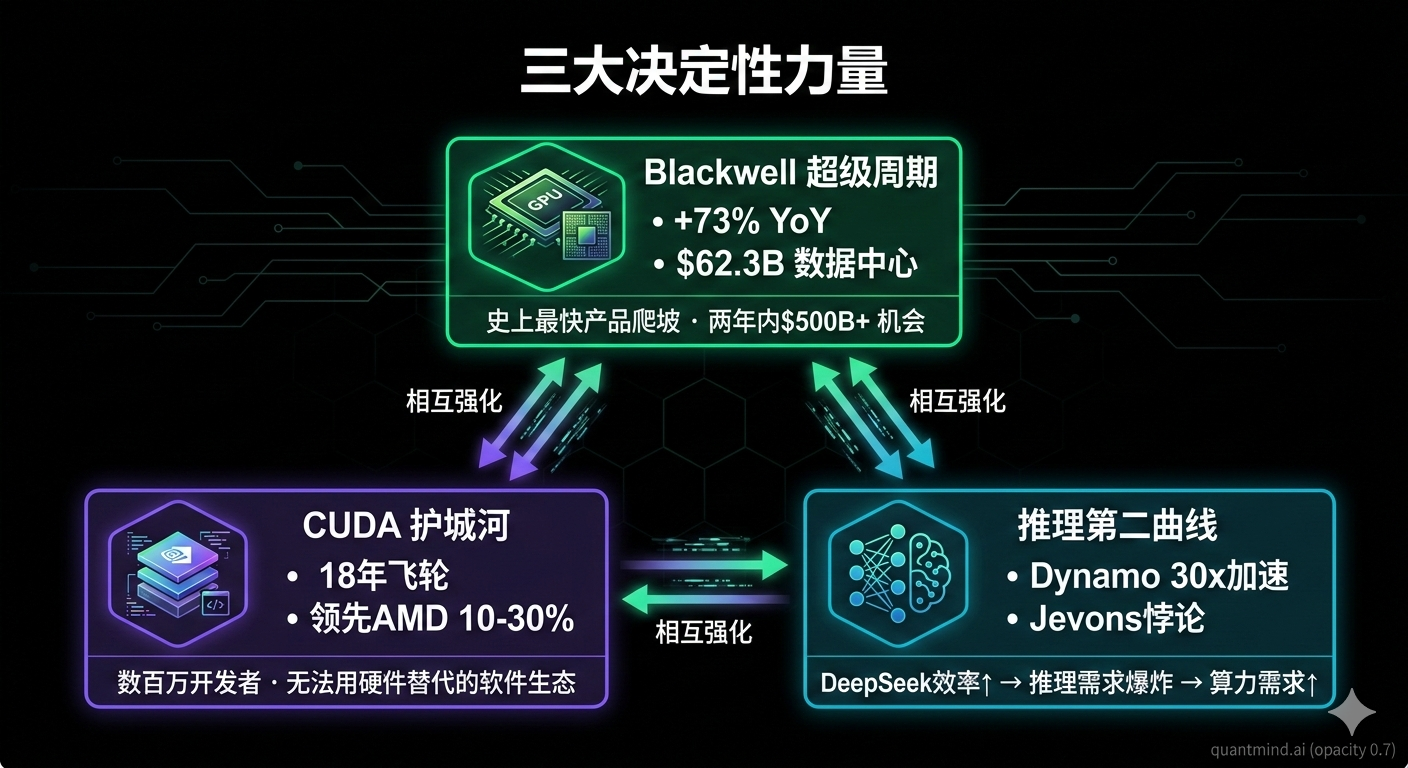
Force 1: Blackwell Supercycle — Unprecedented Product Ramp Speed
Blackwell already accounted for roughly two-thirds of Data Center revenue in Q4 (~$41B of $62.3B). CFO Colette Kress stated: “Our data center business has grown nearly 13x since ChatGPT emerged.”
Jensen Huang made clear on the earnings call: “The world is now awakened to the agentic AI inflection.”
The hyperscaler heavyweights (Google, Microsoft, Amazon, Meta) have budgeted a combined ~$700B in AI CapEx for 2026, which Jensen called “just the beginning.”
Force 2: The CUDA Moat — An 18-Year Software Flywheel, Not a Hardware Advantage
AMD’s MI300X leads on memory specs (192GB vs H100’s 80GB), yet CUDA’s ecosystem delivers a measured 10-30% performance lead over AMD’s ROCm stack across most AI workloads. This is not a silicon moat — it is 18 years of developer ecosystem accumulation: millions of developers and hundreds of thousands of optimized model libraries. What AMD needs to rebuild is not hardware, but the entire software ecosystem.
Force 3: The Inference Era — NVIDIA’s Second Growth Curve
DeepSeek was initially read as a threat to NVIDIA; the reality is the opposite. More efficient inference models lower cost thresholds, spawning more AI applications and driving greater total compute demand (Jevons Paradox). NVIDIA’s Dynamo inference optimization software boosts DeepSeek-R1 token generation speed by 30x on GB200.
Key Earnings Data
| Metric | Q4 FY2026 | YoY | vs Consensus |
|---|---|---|---|
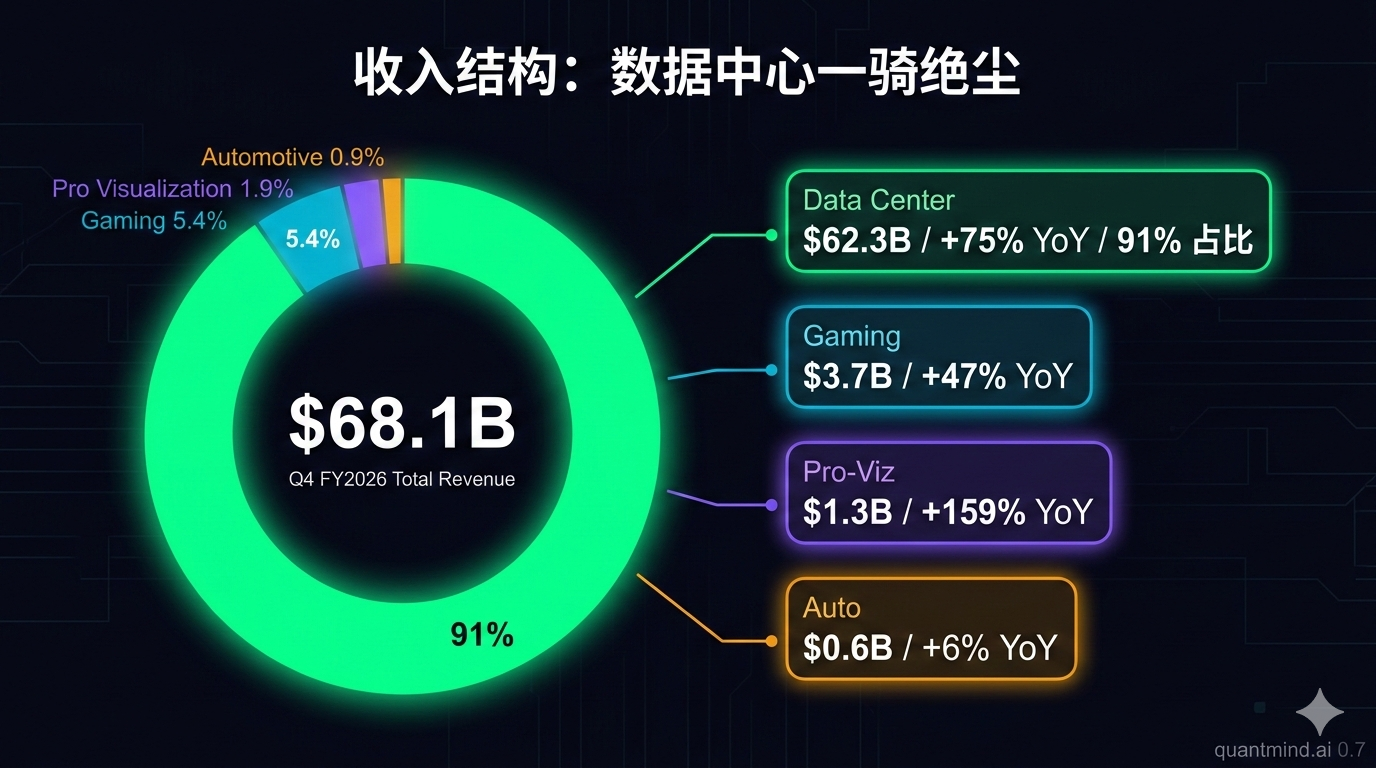
| Total Revenue | $68.1B | +73% | Beat $65.6B |
| Data Center | $62.3B | +75% | 91% of total |
| Gaming | $3.7B | +47% | QoQ -13% (seasonal) |
| Automotive | $0.6B | +6% | Steady growth |
| Gross Margin | 75.0% | +1.5pp | Expanding |
| EPS (GAAP) | $1.76 | +94% | Beat $1.52 |
| Q1 FY27 Guidance | $78.0B +/-2% | — | Beat $72B |
| Full-Year FCF | ~$90B | — | FCM ~42% |
Valuation Matrix
Scenario Analysis
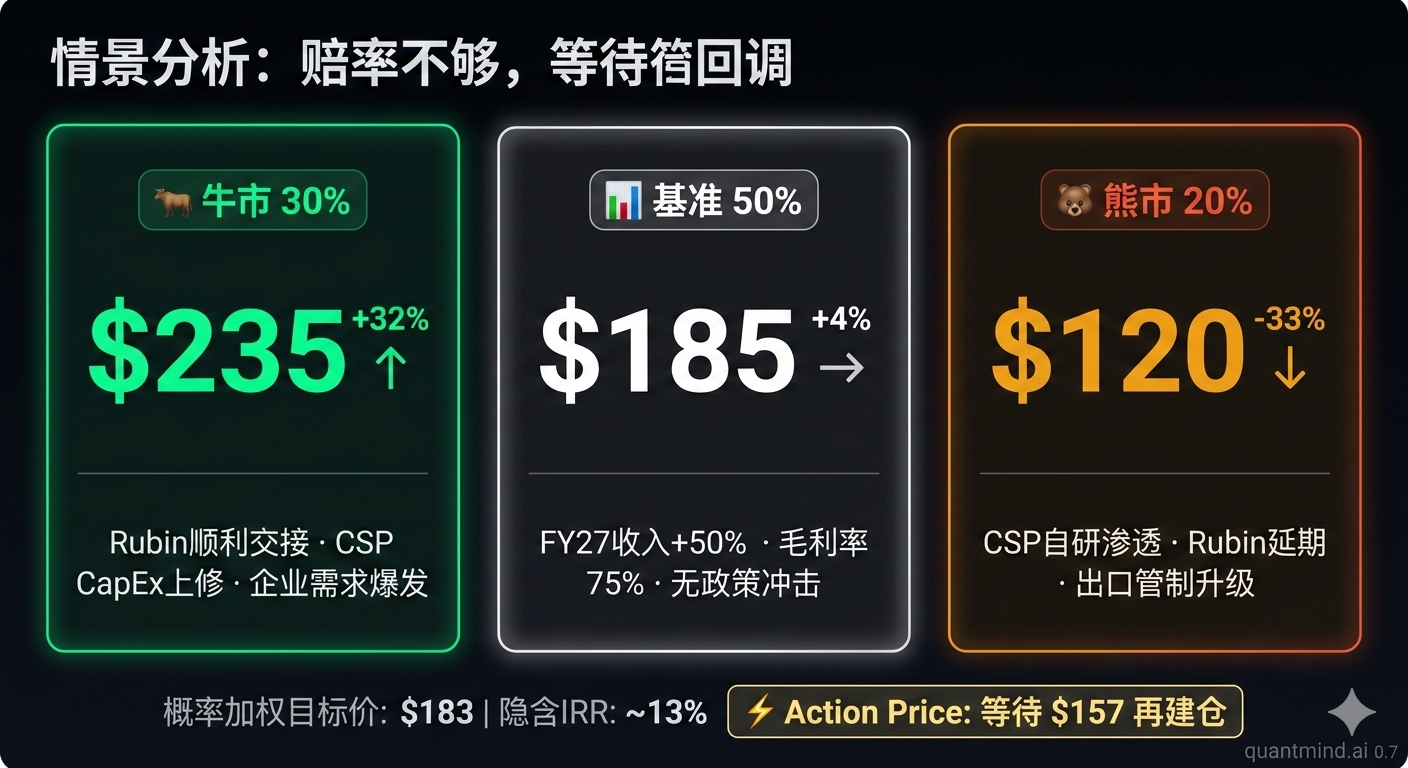
| Scenario | Probability | 12M Target | Return | Key Assumptions |
|---|---|---|---|---|
| Bull | 30% | $235 | +32% | Smooth Rubin transition, CSP CapEx revised upward |
| Base | 50% | $185 | +4% | FY27 revenue +50%, gross margin 75% |
| Bear | 20% | $120 | -33% | Accelerated CSP in-house chip adoption, Rubin delays |
Probability-Weighted Target: $183 | Implied IRR: ~13%
IRR below our 15% hurdle — at $178, no position initiated
Action Price
- Initial Entry: $157 (15% margin of safety)
- Add Position: $140 (25% margin of safety)
- Full Position: $120-130 (contingent on intact fundamentals)
Variant View
Market Consensus: Blackwell supercycle continues; valuation is reasonable to slightly cheap.
Our View: The market is underpricing two non-linear risks:
-
Blackwell-to-Rubin Generational Transition Window (2H 2026) — may create a supply gap similar to the Hopper-to-Blackwell transition slowdown, but with amplified impact at a $4T market cap
-
CSP In-House Chip Penetration — full replacement is not required. Even shifting 10-15% of workloads to internal silicon would compress growth expectations from +50% to +30%, triggering a sharp market repricing
Why the Market Is Wrong: The market treats “AI CapEx grows forever” as the base case, but every infrastructure buildout cycle in history has experienced 1-2 quarters of digestion.
Six Investment Philosophy Perspectives
| Perspective | Verdict | Core Rationale |
|---|---|---|
| Quality Compounders (Buffett/Munger) | PASS | Hardware companies struggle to sustain 20-year pricing power |
| Visionary Growth (Baillie Gifford) | Long | AI is an industrial-revolution-scale transformation; NVIDIA is the only full-stack beneficiary |
| Fundamental Long/Short (Tiger Cubs) | Limited Long | Wait for $155-165; current risk/reward unattractive |
| Deep Value (Klarman) | PASS | Private buyer price ~$140-150; no margin of safety |
| Catalyst-Driven (Tepper/Ackman) | Long — Pending Trigger | Catalysts: Q1 >$82B or official Rubin shipment |
| Macro Tactical (Druckenmiller) | Neutral | Liquidity supportive, but strong dollar and export controls require hedging |
Key Risks
Red Flags (Immediate Attention)
Net Insider Selling: CFO Colette Kress and multiple executives have net sold over $150M+ in 2026 year-to-date with zero purchases on record. Jensen Huang says “AI is only going to get better,” but the CFO is selling stock.
Yellow Flags (Ongoing Monitoring)
- Falsifiability of the “Compute = Revenue” Narrative: When CSPs begin reporting AI ROI below expectations, the narrative could reverse rapidly
- Extreme Consensus: 95% of analysts rate Buy — where does alpha come from?
- 91% Data Center Concentration: Extreme single-point-of-failure risk
Pre-Mortem: If We Lose Money in 2 Years
Failure Path A (40%): CapEx digestion cycle + CSP in-house chip migration — Data Center QoQ growth falls below 5% for two consecutive quarters — P/E compresses from 21x to 15x — stock reaches $100-120
Failure Path B (30%): TSMC N3 capacity bottleneck during Rubin generational transition causes a 2-quarter delay — revenue vacuum — confidence collapse
Failure Path C (20%): Escalated export controls + tightening US AI regulation — suppress hyperscaler AI CapEx budgets
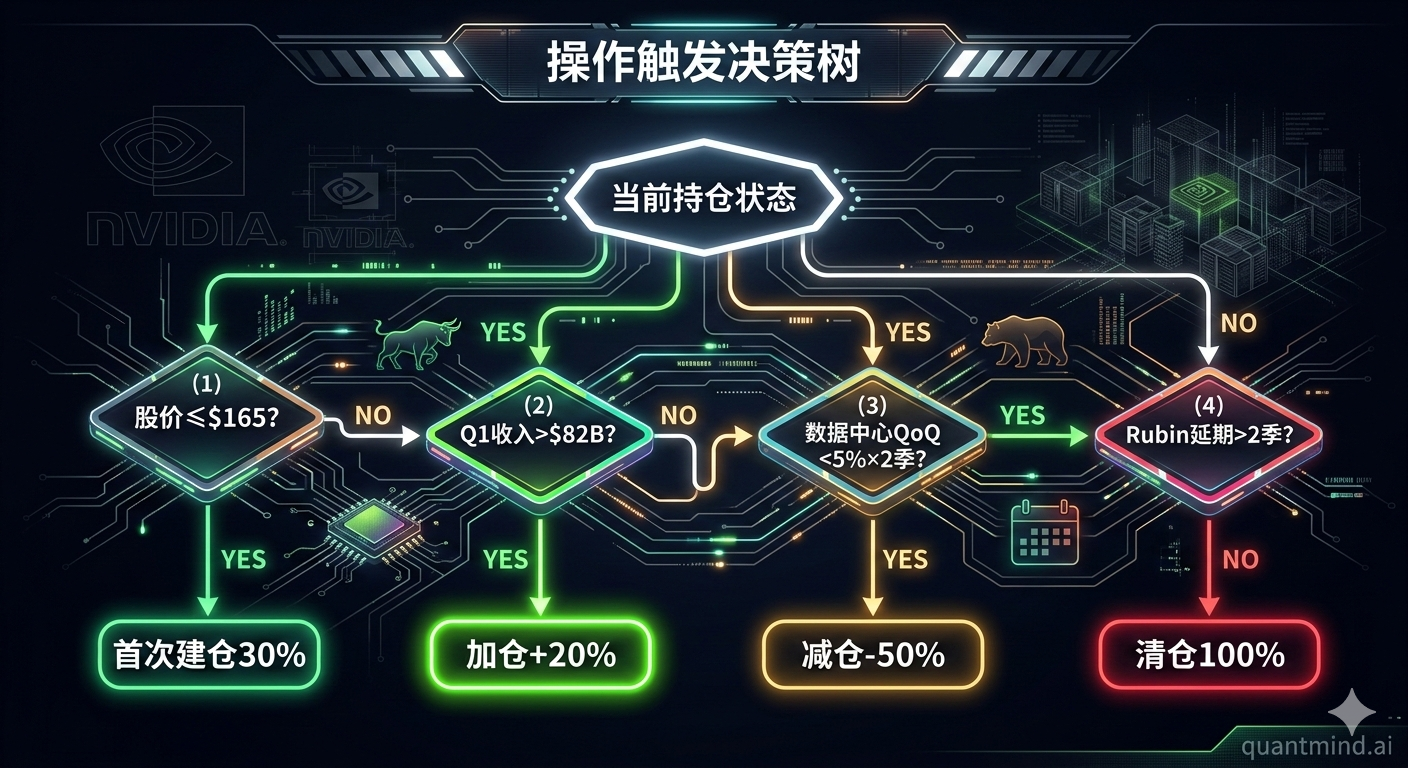
Action Triggers (Quantifiable Operating Conditions)
| Signal | Action | Size |
|---|---|---|
| Stock pulls back to $155-165 | Initiate position | 30% |
| Q1 FY27 revenue exceeds $82B | Add to position | +20% |
| Stock pulls back to $130-140 (fundamentals intact) | Add to position | +25% |
| Data Center QoQ <5% for 2 consecutive quarters | Reduce position | -50% |
| Any hyperscaler cuts AI CapEx >20% | Reduce position | -30% |
| Rubin delayed >2 quarters + guidance well below consensus | Exit position | 100% |
Conclusion
$NVDA is the best AI infrastructure company on the planet. At $178, the risk/reward doesn’t clear our 15% IRR hurdle. Wait for $155-165.
Analysis based on NVIDIA Q4 FY2026 earnings reported February 25, 2026. Data sources: NVIDIA Newsroom, Motley Fool earnings transcript, SemiAnalysis, CNBC, Fortune. Not investment advice. For research purposes only.