Mar 22, 2026
The Munitions Super-Cycle: Why Defense Stocks Are the Best-Executing Sector
Operation Epic Fury x NATO Rearmament x Neoprime Disruption. Full analysis of 10 defense stocks — 7 of 10 have 100% earnings beat rates.
Part 2 of “The Geopolitical Edge” Investment Series
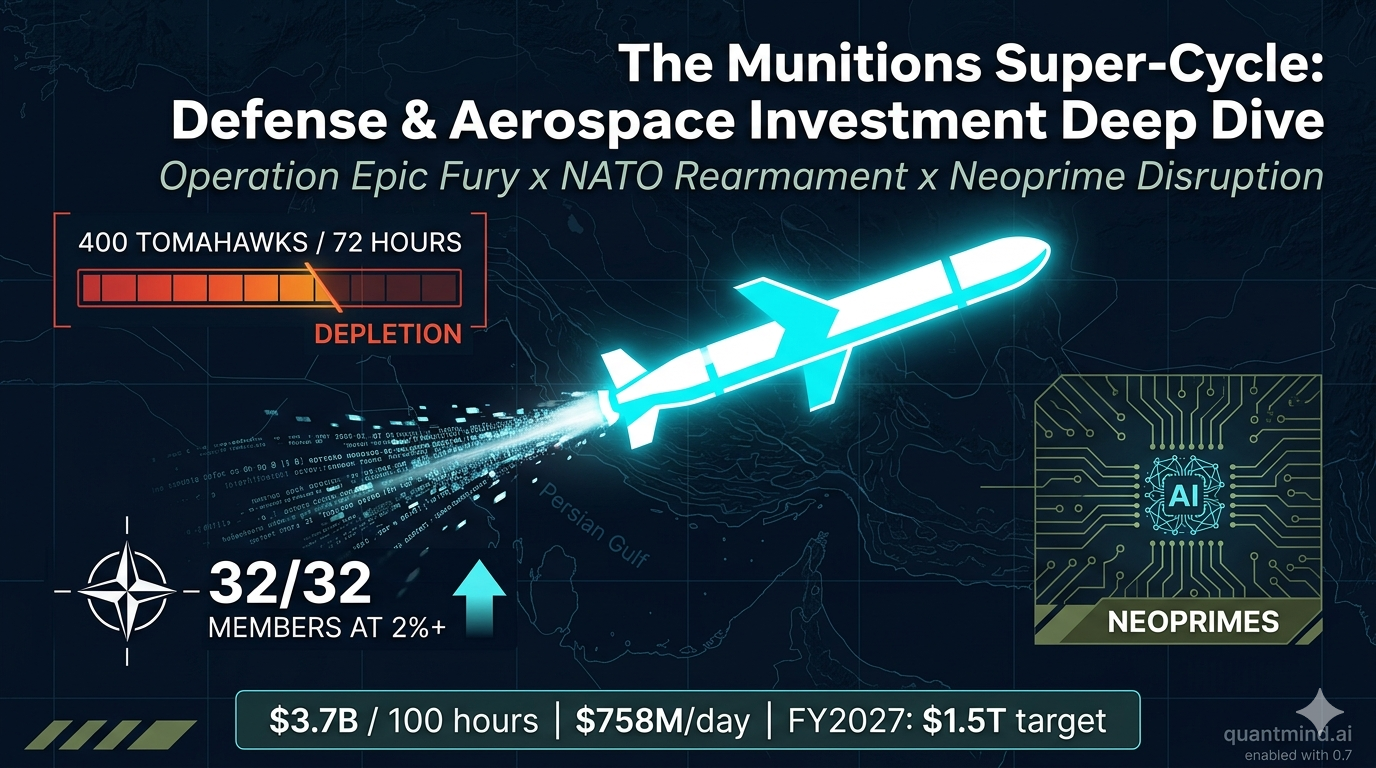
400 Tomahawk missiles. 72 hours. 10% of the entire US inventory — gone.
That’s what Operation Epic Fury consumed in its opening salvo against Iran. The bill for the first 100 hours: $3.7 billion. The Pentagon is now burning through $758 million per day, has submitted a $200B+ supplemental request, and FY2027 defense spending is targeting $1.5 trillion.
But here’s what the market is missing: 7 out of 10 defense stocks have 100% earnings beat rates over the last 4 quarters. This isn’t just a spending thesis — it’s an execution story.
I ran full fundamental analysis on 10 defense stocks — primes, mid-tiers, and AI-native “neoprimes” — across the complete toolkit: valuation, financial health, earnings quality, peer comparisons, intrinsic value. Here’s the complete breakdown.
TL;DR: - Top Conviction: LDOS (Leidos) — #2 cheapest, #1 quality, 55% upside, 100% beat rate, Altman Z 3.94 - Best Prime: GD — strongest balance sheet (Z-score 4.24), 100% beats, +14.3% revenue growth - Highest Conflict Exposure: RTX — $251B backlog, makes Tomahawk/Patriot, but expensive at 40x P/E - Best Growth Play: KTOS — drone pure-play validated by Iran conflict, 79x forward P/E - Most Controversial: PLTR — $10B Army deal, 40.9% operating margins, but 81x forward P/E
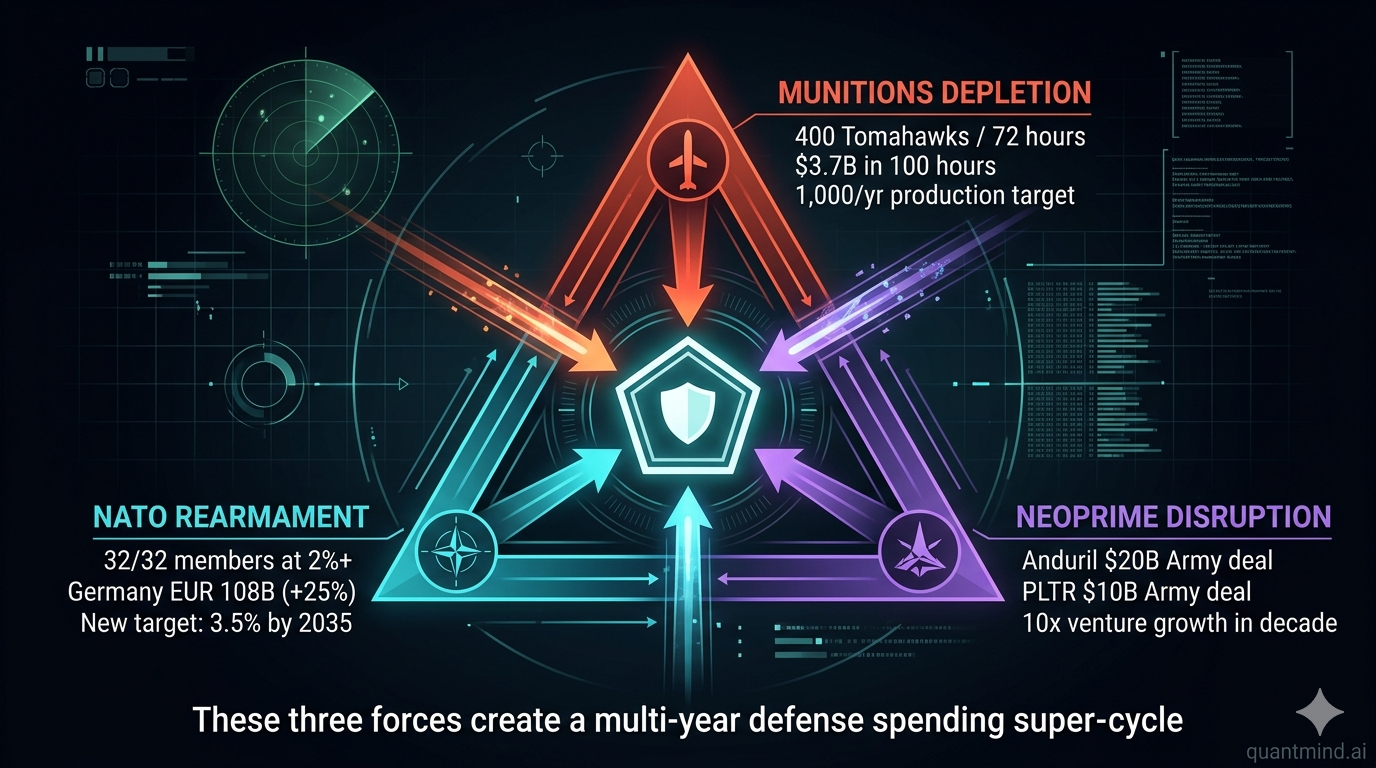
Three Forces Driving Defense Spending
Force 1: Operation Epic Fury — The Munitions Depletion Catalyst
The US-Israeli strikes on Iran (February 28, 2026) initiated munitions consumption unprecedented in modern warfare:
- 400 Tomahawks fired in 72 hours — 10% of US inventory
- 2,000+ munitions expended in first 100 hours
- $3.7 billion cost in first 100 hours (CSIS); $758M/day ongoing
- Pentagon targeting 1,000 Tomahawks/year (RTX) and 1,100 JASSM/year (LMT) — up from a prior-year request of just 57 Tomahawks
- $50 billion emergency supplemental moving through Congress
- $200B+ supplemental submitted to OMB
This creates a multi-year munitions replenishment super-cycle valued at over $20.4 billion. This isn’t discretionary — it’s mandatory inventory rebuilding.
Force 2: NATO’s Historic Rearmament
For the first time ever, all 32 NATO members meet or exceed 2% of GDP defense spending. New aspirational target: 3.5% by 2035.
- Poland: 4.48% of GDP — NATO’s highest
- Germany: EUR 108.2B budget (+25% YoY), EUR 377B procurement plan, ordering 3,000 Boxer APCs + F-35s
- France: EUR 68.5B, targeting EUR 100B/year by decade’s end
- US: FY2026 budget $1.01 trillion; FY2027 targeting $1.5 trillion
Force 3: Rise of the “Neoprimes”
AI-native defense companies are disrupting legacy contractors:
- Anduril ($30.5B valuation): $20B Army enterprise deal
- Palantir ($360B market cap): $10B Army deal, AI generates 30x more options in under 10 seconds
- Shield AI ($5.6B): Forming consortia with PLTR and Anduril
Venture investment in defense tech increased more than tenfold in the past decade.
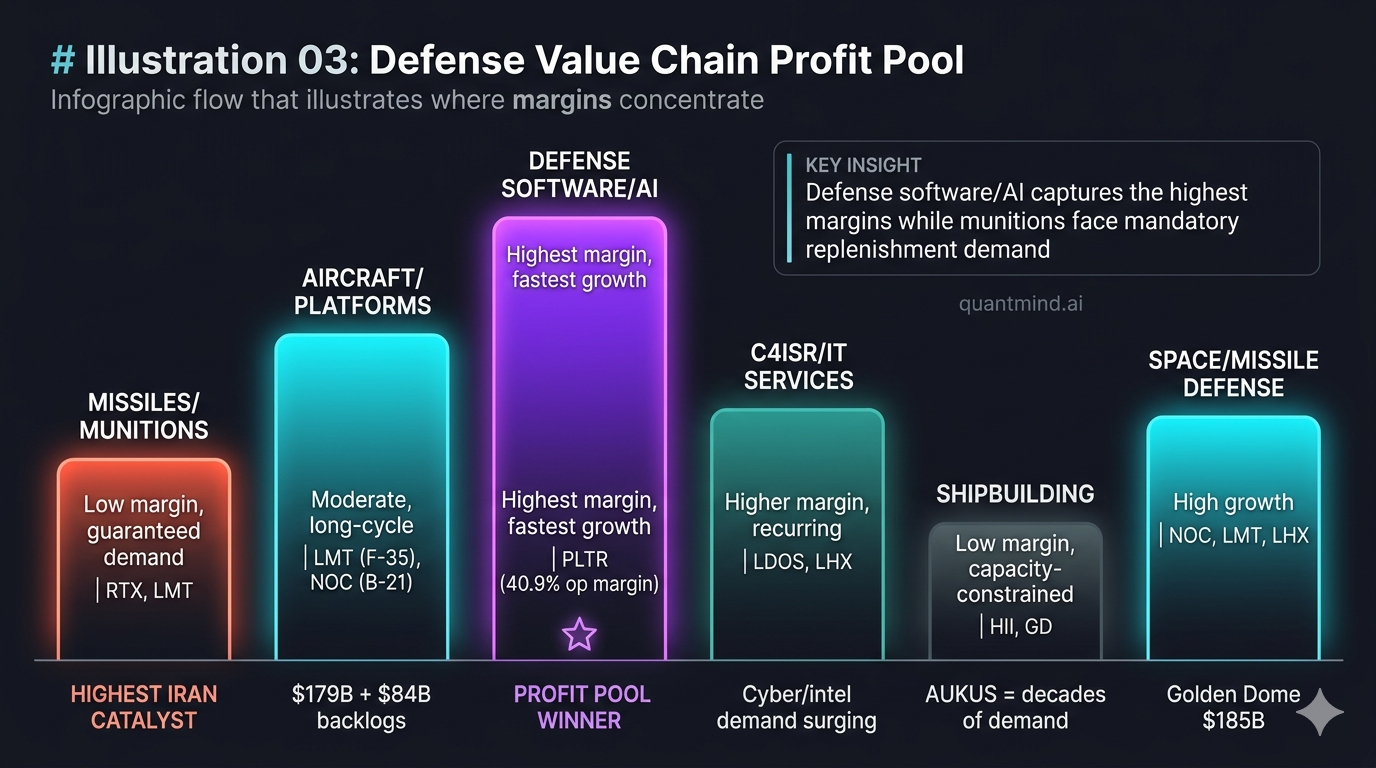
Where the Money Is: Defense Profit Pool
| Segment | Margin Profile | Key Players | Iran/NATO Catalyst |
|---|---|---|---|
| Missile/Munitions | Low margin, guaranteed demand | RTX, LMT | VERY HIGH — depletion drives mandatory replenishment |
| Aircraft/Platforms | Moderate, long-cycle | LMT (F-35), NOC (B-21) | HIGH — NATO F-35 orders accelerating |
| Defense Software/AI | Highest margin, fastest growth | PLTR (40.9% op margin), KTOS | HIGH — AI battlefield demand structural |
| C4ISR/IT Services | Higher margin, recurring | LDOS, BAH, LHX | MODERATE — cyber/intel demand surges |
| Shipbuilding | Low margin, capacity-constrained | HII, GD | MODERATE — AUKUS subs are decades-long |
| Space & Missile Defense | High growth | NOC, LMT, LHX | HIGH — Golden Dome $185B program |
The Power Ranking: 10 Defense Stocks Analyzed
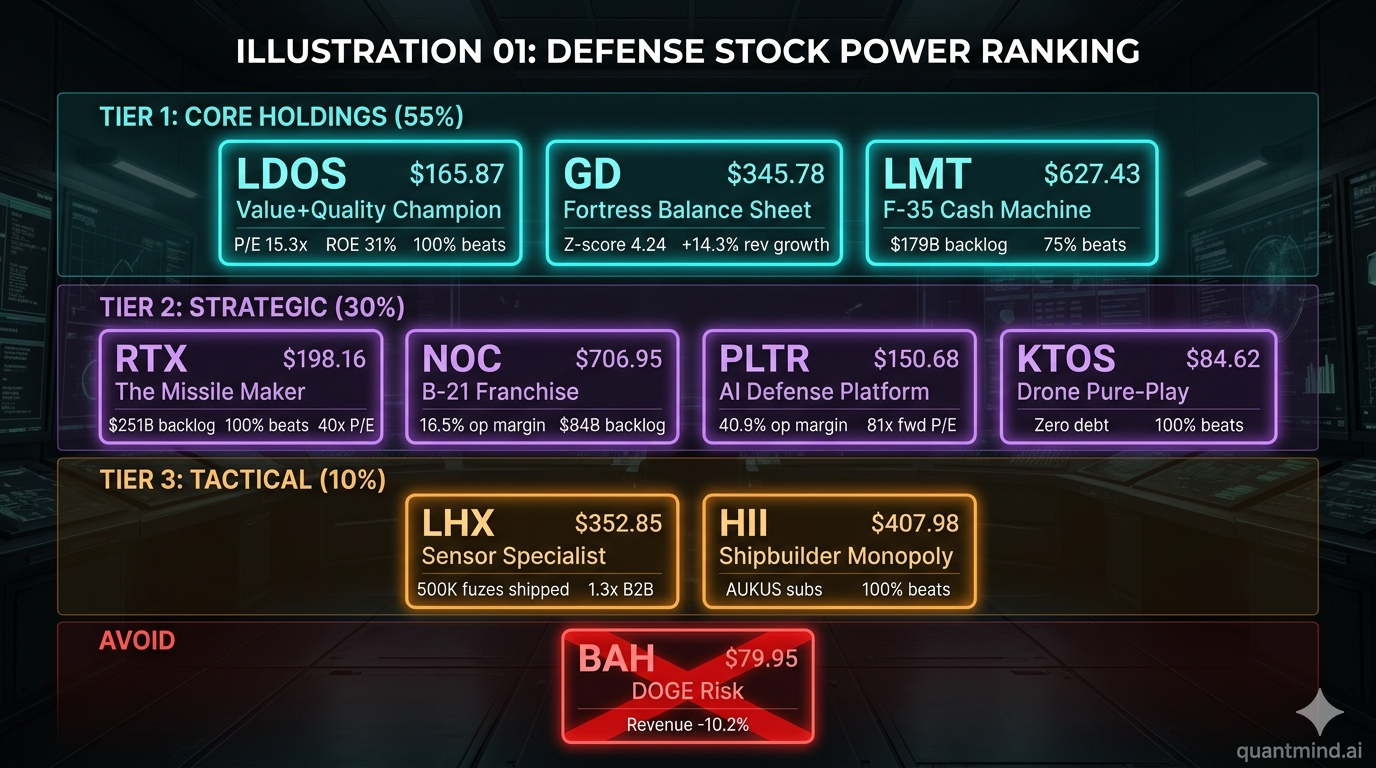
Tier 1: Core Holdings
LDOS — Leidos | $165.87 | Market Cap: $21B
The Value + Quality Champion
| Metric | Value | Signal |
|---|---|---|
| P/E (TTM) | 15.3x | #2 cheapest |
| Forward P/E | 14.8x | Attractive |
| ROE | 31.0% | #1 quality |
| FCF Yield | 5.2% | Strong |
| Beat Rate | 100% (4/4) | Perfect |
| Surprise Trend | Improving (+24.8%) | Analysts still behind |
| Altman Z-Score | 3.94 | SAFE |
| Revenue Growth | -3.6% | Concern |
Bull case: Rare combination of #2 cheapest and #1 quality. 100% beat rate with improving surprises. Largest US government IT services provider with deep intelligence/defense entrenchment. P/E baseline implies 55% upside.
Bear case: Revenue declined 3.6% — the only negative growth in the universe. If this reflects contract losses, the value thesis weakens.
Geopolitical edge: Cyber operations, intelligence analytics, and digital modernization — all accelerated by Iran conflict.
Action: BUY. Best risk/reward in defense.
GD — General Dynamics | $345.78 | Market Cap: $93B
The Fortress Balance Sheet
| Metric | Value | Signal |
|---|---|---|
| P/E (TTM) | 17.2x | Moderate |
| Forward P/E | 15.7x | Attractive |
| ROE | 17.7% | Healthy |
| Revenue Growth | +14.3% | Best in universe |
| Beat Rate | 100% (4/4) | Perfect |
| Altman Z-Score | 4.24 | Highest in universe |
| Debt/Equity | 38.0% | Conservative |
Bull case: Strongest balance sheet in defense (Z-score 4.24, D/E 38%) AND highest revenue growth (+14.3%). Dual moat: Gulfstream jets (high-margin) + combat systems (Abrams, Stryker). Poland ordering 250+ Abrams tanks.
Bear case: Gulfstream is cyclical — recession would compress the high-margin segment.
Action: BUY. Fortress balance sheet + best growth + 100% beats = high conviction.
LMT — Lockheed Martin | $627.43 | Market Cap: $145B
The F-35 Cash Machine
| Metric | Value | Signal |
|---|---|---|
| P/E (TTM) | 29.2x | Above average |
| Forward P/E | 19.6x | Reasonable |
| FCF | $5.28B | Strong |
| Revenue | $75.0B | +9.1% YoY |
| Beat Rate | 75% (3/4) | Q3 one-time charge |
| Backlog | ~$179B | 2.4x revenue |
| Altman Z-Score | 3.65 | SAFE |
Bull case: F-35 is a generational franchise ($15B+/yr for decades). $179B backlog. THAAD/PAC-3 deployed in Iran theater. NATO F-35 orders accelerating.
Bear case: Gross margins structurally low (10%). D/E at 339% from aggressive buybacks.
Action: HOLD/ACCUMULATE. Fairly valued. Core defense holding.
Tier 2: Strategic Positions
RTX Corporation | $198.16 | Market Cap: $267B — The Missile Maker
$251B backlog (largest in A&D globally). Makes Tomahawk, Patriot, NASAMS. 100% beat rate. But 40x trailing P/E is expensive. HOLD — wait for pullback to $170-180.
NOC — Northrop Grumman | $706.95 | Market Cap: $101B — The B-21 Franchise
B-21 Raider ($200B+ lifecycle). Sentinel ICBM (sole source). Best operating margins among primes (16.5%). Golden Dome exposure. HOLD — fair value.
Tier 3: Growth / Tactical
PLTR — Palantir | $150.68 | Market Cap: $360B — The AI Defense Platform
$10B Army deal. 40.9% operating margins (software-tier). Zero debt, $5.2B cash. 100% beats. But 81x forward P/E prices perfection. SPECULATIVE HOLD — only for AI-military believers.
KTOS — Kratos | $84.62 | Market Cap: $16B — The Drone Pure-Play
Drone warfare validated by Iran/Ukraine. Makes autonomous drones (Valkyrie, XQ-58). Zero debt, 100% beats. But 2.9% operating margin and negative FCF. SPECULATIVE BUY — drone thesis is real.
LHX — L3Harris | $352.85 | Market Cap: $66B — The Sensor Specialist
Shipped 500,000 fuzes in 2025 (+80% YoY). 1.3x book-to-bill. Golden Dome sensors. 100% beats. HOLD — good execution, fully valued.
HII — Huntington Ingalls | $407.98 | Market Cap: $16B — The Shipbuilder
One of two yards building nuclear vessels. AUKUS submarines. 100% beats. But 5.9% operating margins. HOLD — monopoly position, low margins.
Avoid
BAH — Booz Allen | $79.95 | Market Cap: $10B — DOGE Risk
Cheapest at 11.9x P/E, highest FCF yield (8.2%). But revenue down 10.2% — worst in universe. DOGE cost-cutting directly threatens consulting contracts. MONITOR — wait for revenue stabilization.
Geopolitical Scenario Matrix
| Stock | Epic Fury Continues | Ceasefire | NATO 3.5% Ramp |
|---|---|---|---|
| LDOS | Strong — cyber/intel surges | Moderate — IT modernization continues | Strong — allied digital transformation |
| GD | Strong — combat systems | Moderate — Gulfstream carries | Very Strong — Abrams exports |
| LMT | Very Strong — missile defense | Moderate — backlog floor | Very Strong — F-35 NATO standard |
| RTX | Very Strong — Tomahawk depletion | Moderate — commercial offsets | Very Strong — Patriot exports |
| PLTR | Strong — AI battlefield | Strong — structural adoption | Strong — allied intel sharing |
| KTOS | Very Strong — drone warfare | Moderate — counter-UAS needed | Strong — NATO drone programs |
Portfolio Construction
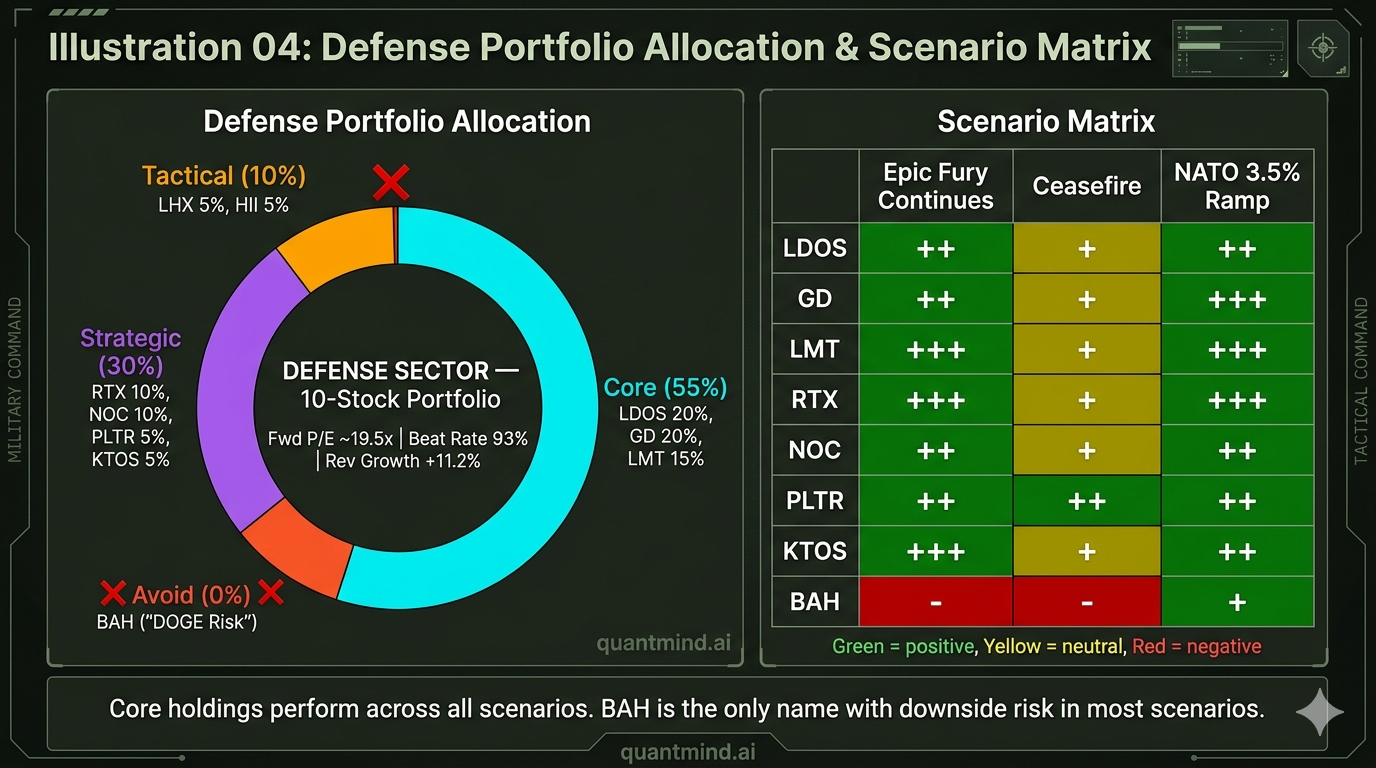
| Tier | Stock | Allocation | Rationale |
|---|---|---|---|
| Core (55%) | LDOS | 20% | Best value+quality combination |
| GD | 20% | Fortress balance sheet + best growth | |
| LMT | 15% | F-35 franchise, missile defense | |
| Strategic (30%) | RTX | 10% | Tomahawk/Patriot, but expensive |
| NOC | 10% | B-21/Sentinel franchise | |
| PLTR | 5% | AI defense platform | |
| KTOS | 5% | Drone warfare optionality | |
| Tactical (10%) | LHX | 5% | Munitions components, sensors |
| HII | 5% | Shipbuilding monopoly | |
| Avoid (0%) | BAH | 0% | DOGE risk |
6 Investment Philosophy Perspectives
| Philosophy | Verdict | Rationale | Biggest Risk |
|---|---|---|---|
| Quality Compounder (Buffett) | LONG GD, LDOS | Fortress balance sheets + durable demand | DOGE spending cuts |
| Imaginative Growth (Baillie Gifford) | LONG PLTR, KTOS | AI + autonomous warfare = paradigm shift | Extreme valuations |
| Fundamental L/S (Tiger Cubs) | LONG LDOS / CAUTIOUS BAH | Value+quality vs DOGE-exposed consulting | Revenue trends |
| Deep Value (Klarman) | LONG BAH (contrarian) | 11.9x P/E, 8.2% FCF yield if DOGE overdone | Revenue keeps declining |
| Catalyst-Driven (Tepper) | LONG RTX, LMT | Supplemental = near-term catalyst | Ceasefire risk |
| Macro Tactical (Druckenmiller) | LONG defense broadly | Generational rearmament across NATO | Budget fatigue |
Variant View
Market consensus: Defense stocks have already re-rated on the Iran conflict. The easy money has been made.
What the market is missing: This isn’t an event — it’s a regime change. All 32 NATO members simultaneously rearming. US targeting $1.5T defense budget. Mandatory munitions replenishment. Drone warfare fundamentally changing force design. 7/10 stocks executing at 100% beat rates. The consensus P/E of ~20-25x treats this as cyclical. It’s structural.
Pre-Mortem: Three Ways This Goes Wrong
-
Quick ceasefire + DOGE cuts. Conflict ends in 3 months, supplemental shrinks, DOGE cuts defense IT 10-15%. Defense stocks give back 15-20%.
-
NATO spending fatigue. European voters rebel against 3.5% GDP spending as economies slow. German procurement plan scaled back.
-
Neoprime disruption. Anduril and venture-backed companies capture increasing contract share, compressing legacy prime margins.
Decision Framework
| Stock | Buy | Add | Reduce | Stop |
|---|---|---|---|---|
| LDOS | $140 | $155 | $200 | $120 |
| GD | $300 | $320 | $400 | $270 |
| LMT | $550 | $590 | $700 | $480 |
| RTX | $170 | $185 | $230 | $150 |
| NOC | $620 | $670 | $800 | $560 |
| PLTR | $100 | $120 | $180 | $80 |
| KTOS | $65 | $75 | $100 | $55 |
Part 2 of “The Geopolitical Edge” series. Part 1: LNG Value Chain available on the blog.
Disclaimer: Research and educational purposes only. Not investment advice. Data as of March 22, 2026.