Mar 22, 2026
The Supply Chain Arms Race: Critical Minerals Investment Deep Dive
China rare earth weapon x Copper supercycle x Defense reshoring. 10 critical minerals stocks analyzed from mega-cap diversified miners to US rare earth pure-plays.
Part 5 of “The Geopolitical Edge” Investment Series
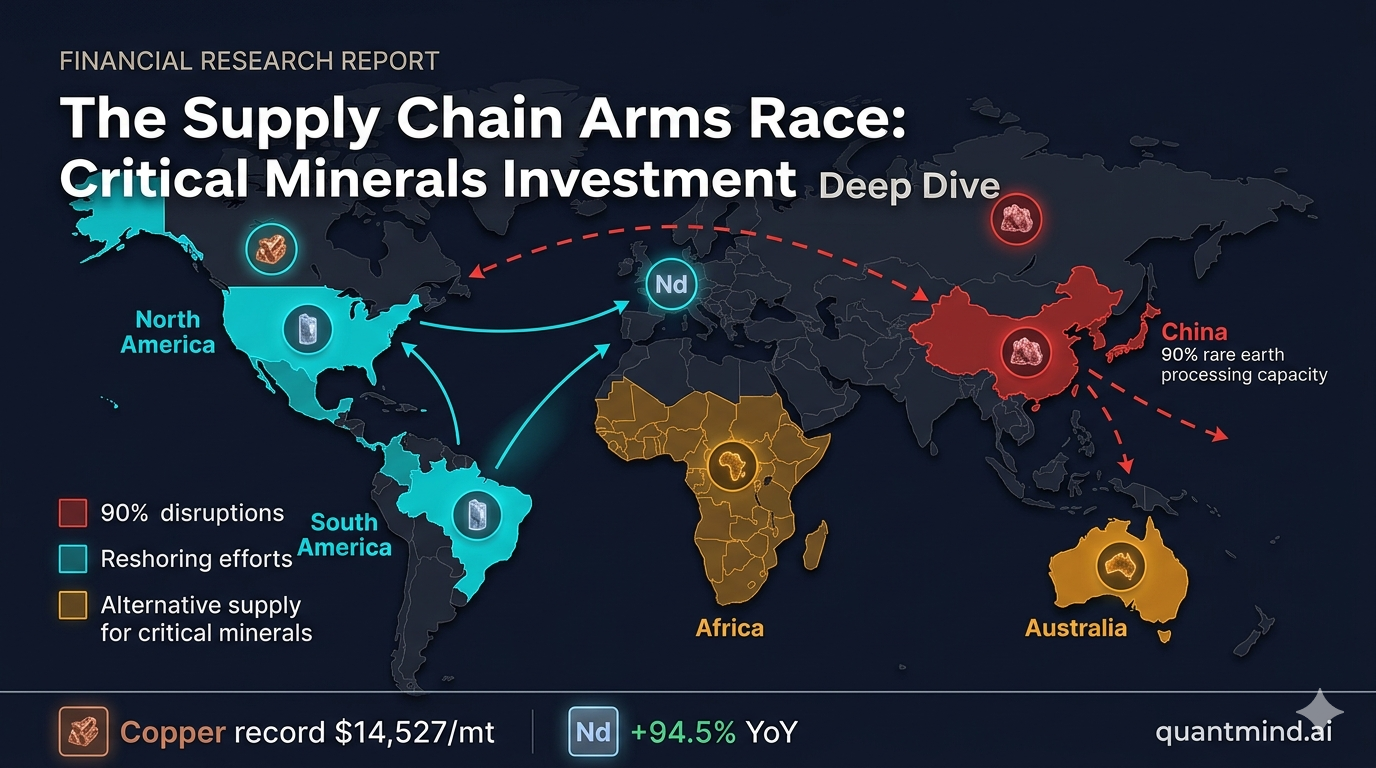
Neodymium up 94.5% in a year. Dysprosium up 163.6%. China controls 90% of rare earth processing — and just weaponized it.
In November 2025, Beijing imposed export controls on gallium, germanium, antimony, and rare earth processing technology — the mineral equivalent of an oil embargo. The Pentagon scrambled: every F-35 contains 920 pounds of rare earths, and the US has exactly one integrated mine-to-magnet facility in the entire Western Hemisphere. Copper hit a record $14,527/mt in January 2026 on structural deficit. The DRC banned cobalt exports. And the $540 million the Pentagon invested in domestic rare earth capacity suddenly looks like the opening ante in a trillion-dollar reshoring supercycle.
This is not a commodity cycle. This is an industrial policy regime change.
I ran full fundamental analysis on 10 critical mineral stocks — rare earth pure-plays, lithium developers, copper kings, and diversified majors — across the complete toolkit: valuation, financial health, earnings quality, peer comparisons, intrinsic value. Here’s the complete breakdown.
TL;DR: - Top Conviction: RIO (Rio Tinto) — cheapest mega-cap miner (P/E 10.5x, EV/EBITDA 5.9x), 4.8% dividend, Arcadium acquisition adds lithium at trough, Graham Number implies +17.5% upside - Best Copper Play: FCX (Freeport-McMoRan) — world’s largest public copper producer, PEG 0.37 (lowest in group), US operations at Morenci/Bagdad, AI data center demand not yet priced - Highest Strategic Optionality: MP Materials — only integrated rare earth mine-to-magnet in the Western Hemisphere, $1.83B cash fortress, but $9B market cap on $275M revenue is priced for perfection - Best Turnaround: TECK (Teck Resources) — post-coal transformation to pure copper/zinc, F-Score 7/9 (best in group), P/B 1.17x, analyst target +17% - Deep Value Dividend: VALE — EV/EBITDA 5.3x, 6.44% yield, multi-metric undervaluation, but China iron ore dependency
Three Forces Driving the Critical Minerals Supercycle
Force 1: China Weaponizes the Mineral Supply Chain
China’s dominance over critical mineral processing is not a risk scenario — it is today’s reality:
- 90% of rare earth processing — even ore mined in Australia or the US gets shipped to China for separation and refining
- 60% of rare earth mining — and growing through African acquisitions
- 70%+ of lithium refining — China processes more lithium than it mines
- 80%+ of cobalt refining — despite the DRC mining 70% of global cobalt
- Export controls imposed November 2025 on gallium, germanium, antimony, and REE processing technology — directly targeting the US defense-industrial base
- Suspension expires November 2026 — creating a ticking clock for Western supply chains
- Neodymium prices surged 94.5% YoY and dysprosium 163.6% as export restrictions bite
- Beijing has demonstrated willingness to weaponize minerals as geopolitical leverage, just as it did with rare earths against Japan in 2010
The strategic calculus is simple: any mineral that flows through China is a weapon that can be turned off. The market has not fully priced the probability that these controls become permanent or expand.
Force 2: Structural Supply Deficits Across Critical Minerals
This is not a demand-pull story alone — supply cannot keep pace:
- Copper: Record $14,527/mt in January 2026. The International Energy Agency projects a 30%+ supply gap by 2030 for electrification targets. New copper mines take 15-20 years from discovery to production. AI data center buildout is adding an entirely new demand vector not in legacy forecasts
- Lithium: Prices rebounding from 2024 lows as EV adoption reaccelerates. China’s lithium refining dominance means even “Western” lithium often transits through Chinese processing. IRA requirements for domestic/ally-sourced battery materials are creating a two-tier pricing market
- Rare Earths: Neodymium and dysprosium are essential for permanent magnets in EVs, wind turbines, and precision-guided munitions. There is no substitute at scale. Western processing capacity is essentially zero outside MP Materials’ Mountain Pass facility
- Cobalt: DRC export ban and quota system restricting supply. Battery chemistries shifting toward lower-cobalt formulations, but defense and aerospace applications remain cobalt-dependent
- The permitting bottleneck: Even with bipartisan support for mining, the average US mine permitting timeline is 7-10 years. This structural lag ensures supply deficits persist through the decade
Force 3: Defense Supply Chain — The National Security Imperative
The Pentagon has moved from studying the problem to spending real money:
- $540 million invested in mine-to-magnet domestic supply chain, including equity stakes in MP Materials
- F-35 contains 920 lbs of rare earths — every fighter jet, guided missile, and satellite depends on materials China controls
- Operation Epic Fury munitions depletion (covered in Part 2 of this series) creates additional demand for rare earth magnets, copper wiring, and specialty metals in precision-guided weapons
- Defense Production Act Title III invoked repeatedly for critical minerals since 2022
- Bipartisan support: Critical minerals reshoring is one of the few areas with genuine cross-party consensus. The IRA (Inflation Reduction Act), CHIPS Act, and proposed ONSHORE Act all channel subsidies toward domestic and allied-nation mineral supply chains
- Section 45X Advanced Manufacturing Production Credits provide direct per-unit subsidies for domestic critical mineral processing — a structural cost advantage for US producers
Where the Money Is: Critical Minerals Profit Pool
| Segment | Margin Profile | Key Players | Reshoring Catalyst |
|---|---|---|---|
| Rare Earth Mining & Magnets | Low margin today, strategic premium | MP | VERY HIGH — only Western integrated producer; DoD contracts |
| Copper Mining | Moderate-high margin, structural deficit | FCX, TECK, BHP, RIO | VERY HIGH — electrification + AI data centers + defense |
| Lithium Production | Cyclical, trough margins today | ALB, LAC, PLL, RIO (via ALTM) | HIGH — IRA domestic sourcing requirements |
| Diversified Majors | High margin, scale advantages | BHP, RIO, VALE | MODERATE-HIGH — copper/nickel pivots underway |
| Iron Ore | High margin, mature | VALE, RIO, BHP | LOW — China-dependent, not reshoring beneficiary |
| Development-Stage | Negative margin, optionality | LAC, PLL | HIGH optionality — DOE loans, IRA credits if/when production starts |
The Power Ranking: 10 Critical Mineral Stocks Analyzed
Tier 1: Core Holdings
RIO — Rio Tinto | ~$83.15 | Market Cap: $104B
The Undervalued Diversified Powerhouse
| Metric | Value | Signal |
|---|---|---|
| P/E (TTM) | 10.5x | CHEAP — below 25th pct |
| Forward P/E | 7.9x | VERY CHEAP |
| EV/EBITDA | 5.9x | Below 25th pct |
| ROE / Net Margin | 17.3% net | Excellent |
| FCF Yield | 4.31% | Attractive |
| Dividend Yield | 4.81% | High yield |
| Altman Z-Score | 2.46 | Grey zone (normal for miners) |
| Debt/EBITDA | 1.14x | Very manageable |
| Interest Coverage | 13.82x | Excellent |
| Beta | 0.65 | Defensive for a miner |
| Graham Number | $97.72 | +17.5% upside implied |
| Analyst Target | $81.00 | -2.6% (conservative) |
Bull case: Multi-metric undervaluation signal — P/E, Forward P/E, and EV/EBITDA all below 25th percentile. The Arcadium Lithium acquisition ($6.7B, completed) adds lithium exposure at trough cycle prices. Kennecott copper mine in Utah is a US domestic asset. Resolution Copper (Arizona JV with BHP) would be one of America’s largest copper mines. The Graham Number at $97.72 implies +17.5% upside, suggesting analyst consensus is too bearish on iron ore demand. $10B annual net income at apparent trough is impressive.
Bear case: Iron ore is 60%+ of revenue and overwhelmingly China-dependent. Arcadium integration risk. Simandou (Guinea) capex and geopolitical risk. Analyst consensus sees stock as fairly valued.
Geopolitical edge: Arcadium gives lithium; Kennecott gives US copper; aluminium/bauxite gives defense-grade materials. RIO is becoming a one-stop shop for Western critical mineral supply chains.
Action: BUY. Best risk/reward in the sector. Cheapest mega-cap miner with optionality from lithium and copper growth.
FCX — Freeport-McMoRan | ~$52.08 | Market Cap: $75B
The Copper King
| Metric | Value | Signal |
|---|---|---|
| P/E (TTM) | 34.3x | Elevated |
| Forward P/E | 16.9x | Reasonable |
| EV/EBITDA | 9.0x | Fair |
| Gross Margin | 37.1% | Strong |
| Operating Margin | 25.1% | Healthy |
| FCF Yield | 1.49% | Low — capex heavy |
| PEG Ratio | 0.37 | LOWEST in group — deeply undervalued on growth |
| Altman Z-Score | 2.29 | Grey zone |
| Debt/EBITDA | 1.13x | Very manageable |
| Interest Coverage | 17.62x | Excellent |
| Analyst Target | $55.57 | +6.7% |
Bull case: Copper is “the new oil” for electrification. FCX is the world’s largest publicly traded copper producer with massive US operations (Morenci, Bagdad, Sierrita, Safford in Arizona). PEG ratio of 0.37 is the lowest in the entire group — the market is dramatically underpricing copper growth. Grasberg underground transition is complete, unlocking declining costs on high-grade ore. AI data center copper demand is an entirely new vector not yet in consensus estimates.
Bear case: Indonesia sovereign risk (smelter requirements). Trailing P/E at 34x looks expensive. FCF yield of only 1.49% after heavy capex. Gold prices may have peaked.
Geopolitical edge: Arizona copper mines directly serve the domestic critical mineral reshoring thesis. Copper is designated as a critical mineral. US-produced copper avoids tariff risks and qualifies for Section 45X credits.
Action: BUY. Best pure-play on the copper structural deficit. US operations provide reshoring tailwind.
TECK — Teck Resources | ~$45.36 | Market Cap: $22B
The Post-Coal Transformer
| Metric | Value | Signal |
|---|---|---|
| P/E (TTM) | 21.7x | Moderate |
| Forward P/E | 16.6x | Reasonable |
| EV/EBITDA | 8.8x | Fair |
| P/B | 1.17x | Near book value — attractive |
| Net Margin | 13.0% | Healthy |
| Piotroski F-Score | 7/9 | BEST in group — improving fundamentals |
| Altman Z-Score | 1.96 | Grey zone |
| Buyback Yield | 4.0% | Active capital return |
| Analyst Target | $53.17 | +17.2% |
| Graham Number | $42.64 | Near current price |
Bull case: The $8.9B coal divestiture to Glencore transformed TECK into a pure copper/zinc play, and the market has not fully repriced it. F-Score of 7/9 — the strongest in this entire peer group — signals fundamentals improving across the board. Net income tripled from 2024 to 2025. P/B of 1.17x is cheap. Active 4% buyback yield. Canadian ally status benefits IRA supply chain compliance. Analyst target implies +17% upside.
Bear case: Chile/Peru political risk (royalty increases). Negative FCF during QB2 expansion phase. Zinc demand linked to cyclical construction. Below 50-day SMA ($54.45) — momentum is negative.
Geopolitical edge: Canadian-headquartered with Western Hemisphere operations. Zinc and copper are critical for defense electronics. Qualifies as ally-sourced under IRA free trade provisions.
Action: BUY. Post-restructuring value story with best fundamental momentum in the group.
Tier 2: Strategic Positions
VALE — Vale S.A. | ~$14.05 | Market Cap: $60B — The Deep Value Dividend Play
| Metric | Value | Signal |
|---|---|---|
| Forward P/E | 6.3x | Cheapest in group |
| EV/EBITDA | 5.3x | Below 25th pct |
| Dividend Yield | 6.44% | Highest in group |
| P/B | 1.75x | Below 25th pct |
| Operating Margin | 28.4% | Strong |
| FCF Yield | 4.82% | Attractive |
| Piotroski F-Score | 6/9 | Moderate-strong |
Multi-metric undervaluation signal: P/E, EV/EBITDA, and P/B all below 25th percentile simultaneously. The 6.44% dividend is the highest in the group. Canadian nickel operations (Voisey’s Bay, Sudbury) provide an ally-sourced angle. Brumadinho/Mariana dam settlement resolution would remove the major overhang. But iron ore is overwhelmingly China-exposed (~60% of sales), Brazilian political risk is real, and the 154% payout ratio means the dividend exceeds current net income. BUY for income — position size reflects China risk.
ALB — Albemarle | ~$156.70 | Market Cap: $18.5B — The Lithium Cycle Play
| Metric | Value | Signal |
|---|---|---|
| Forward P/E | 19.8x | Reasonable if earnings recover |
| FCF (TTM) | $692.5M | Positive despite net losses |
| Dividend Streak | 31 years | Dividend aristocrat |
| Altman Z-Score | 1.78 | DISTRESS boundary |
| Interest Coverage | 0.40x | RED FLAG |
| PEG Ratio | 1.24 | Reasonable for growth |
Classic cyclical trough play. The world’s largest lithium producer is losing money at trough prices, but FCF remains positive ($692M), the 31-year dividend growth streak signals management discipline, and forward P/E of 19.8x implies analysts expect a massive earnings swing to $7.91 EPS in 2026. Kings Mountain (NC) mine restart provides a domestic production angle. But Altman Z-Score at 1.78 (distress boundary) and interest coverage of 0.40x are genuine red flags — this is not a “safe” position. SPECULATIVE BUY — for investors with a 2-3 year lithium price recovery thesis.
BHP — BHP Group | ~$65.27 | Market Cap: $166B — The Quality Fortress
| Metric | Value | Signal |
|---|---|---|
| FCF Yield | 5.97% | BEST in group |
| Gross Margin | 83.1% | EXCEPTIONAL |
| Operating Margin | 39.3% | Best-in-class |
| Altman Z-Score | 3.03 | SAFE zone |
| Interest Coverage | 24.76x | EXCEPTIONAL |
| Analyst Target | $53.33 | -18.3% downside |
BHP is a financial fortress — safe Z-Score, best FCF yield (5.97%), best margins (83% gross, 39% operating), and exceptional interest coverage. Escondida (world’s largest copper mine) and Olympic Dam (copper/uranium) provide critical mineral exposure. Resolution Copper (Arizona JV with RIO) would be transformative. But ALL valuation models and analyst targets indicate BHP is trading ABOVE fair value. The -18% analyst target downside is significant. HOLD — highest quality, but overvalued. Accumulate on pullbacks below $55.
MP — MP Materials | ~$50.60 | Market Cap: $9B — The Strategic National Asset
| Metric | Value | Signal |
|---|---|---|
| Forward P/E | 194.0x | Extreme premium |
| P/S | 32.6x | Very high |
| Gross Margin | 30.0% | Positive but compressed |
| Operating Margin | -45.6% | Negative — investment phase |
| Cash | $1.83B | Fortress |
| Net Cash | $795.6M | No solvency risk |
| Altman Z-Score | 3.75 | SAFE zone |
| Analyst Target | $70.92 | +40.2% |
MP operates the only integrated rare earth mine-to-magnet facility in the Western Hemisphere (Mountain Pass, California + Fort Worth, TX magnetics plant). This is an irreplaceable strategic asset in a world where China controls 90% of REE processing and has weaponized export controls. The Pentagon has taken an equity stake. Revenue rebounding (+35% YoY) and analyst target implies +40% upside. But the valuation is extreme: $9B market cap on $275M revenue and -$86M net income. The magnetics segment is pre-revenue and driving losses. Traditional valuation models do not apply — this is a strategic asset play. SPECULATIVE BUY — only for investors who believe rare earth reshoring is a national security imperative. Size accordingly.
Tier 3: Speculative / Avoid
LAC — Lithium Americas | ~$3.71 | Market Cap: $1.3B — The Thacker Pass Bet
Largest known lithium deposit in the US (13.7M tonnes LCE). $2.26B DOE loan (largest for a lithium project). GM $650M equity investment. But zero revenue, zero production, F-Score 1/9, 3.04 beta, and rapid share dilution (+21% YoY). This is project finance, not an operating company. SPECULATIVE — pure optionality on US lithium production (2027-2028 timeline). Position size must reflect binary risk.
PLL — Piedmont Lithium | ~$7.25 | Market Cap: $200M — The Micro-Cap Lottery Ticket
Trading at 0.72x book value with two US projects (Carolina Lithium mine in NC, Tennessee Lithium processing). Only 23 employees. Zero mine production. F-Score 2/9. Revenue comes from lithium trading, not production. Analyst target implies +42% upside, but permitting challenges and micro-cap liquidity risk are severe. SPECULATIVE — only for small, diversified positions. Not institutional-grade.
ALTM — Arcadium Lithium | ~$5.84 | Market Cap: $6.3B — Merger Arb / Avoid
Being acquired by Rio Tinto for $6.7B (~$5.85/share). Trading at deal value with essentially zero spread. Altman Z-Score 1.14 (deep distress), F-Score 2/9. NO ACTIONABLE THESIS — buy RIO instead for lithium exposure through Arcadium’s assets.
Geopolitical Scenario Matrix
| Stock | China Controls Tighten | Controls Expire / Ease | Copper Supercycle | Lithium Recovery | US Reshoring Accelerates |
|---|---|---|---|---|---|
| RIO | Moderate — iron ore risk, lithium benefit | Moderate — less urgency for Arcadium premium | Very Strong — copper growth | Strong — Arcadium | Strong — Kennecott, Resolution |
| FCX | Strong — US copper premium | Moderate — less supply anxiety | Very Strong — pure play | N/A | Very Strong — Arizona mines |
| TECK | Strong — ally-sourced copper | Moderate | Strong — QB2 ramp | N/A | Strong — Canadian ally |
| VALE | Weak — China iron ore risk | Moderate | Moderate — growing copper | N/A | Weak — Brazil-focused |
| ALB | Strong — lithium price surge | Weak — less reshoring premium | N/A | Very Strong — #1 producer | Moderate — Kings Mountain |
| BHP | Moderate — copper up, iron ore mixed | Moderate | Very Strong — Escondida | N/A | Moderate — Resolution pending |
| MP | Very Strong — monopoly pricing power | Weak — Chinese competition resumes | N/A | N/A | Very Strong — DoD contracts |
| LAC | Strong — US supply premium | Weak — less urgency | N/A | Strong — if prices recover | Very Strong — DOE-backed |
Portfolio Construction
| Tier | Stock | Allocation | Rationale |
|---|---|---|---|
| Core (50%) | RIO | 20% | Cheapest mega-cap, lithium+copper optionality, 4.8% dividend |
| FCX | 20% | Best copper pure play, US operations, PEG 0.37 | |
| TECK | 10% | Post-restructuring value, best F-Score, +17% target | |
| Strategic (30%) | VALE | 10% | Deep value + 6.4% yield, China risk sized accordingly |
| ALB | 10% | Lithium cycle recovery, world’s #1 producer | |
| BHP | 5% | Quality anchor, accumulate on dips | |
| MP | 5% | Strategic optionality on rare earth reshoring | |
| Tactical (15%) | LAC | 5% | Thacker Pass optionality |
| PLL | 5% | Below-book US lithium option | |
| Cash | 5% | Dry powder for pullbacks | |
| Avoid (0%) | ALTM | 0% | Merger arb — buy RIO instead |
Portfolio characteristics: Weighted average dividend yield ~3.8%. Weighted average forward P/E ~11x. Blended exposure: ~40% copper, ~25% diversified/iron ore, ~20% lithium, ~15% rare earths.
6 Investment Philosophy Perspectives
| Philosophy | Verdict | Rationale | Biggest Risk |
|---|---|---|---|
| Quality Compounder (Buffett) | LONG RIO, BHP | Fortress balance sheets, durable demand, high dividends, wide moats in essential commodities | Iron ore China demand slows |
| Imaginative Growth (Baillie Gifford) | LONG MP, LAC | Rare earth reshoring and US lithium production are generational opportunities; 10x upside if execution succeeds | Extreme valuations, pre-revenue risk |
| Fundamental L/S (Tiger Cubs) | LONG TECK, FCX / SHORT overvalued peers | Best fundamental momentum (F-Score 7), PEG 0.37, post-restructuring re-rating vs priced-to-perfection names | Copper price cyclicality |
| Deep Value (Klarman) | LONG VALE | EV/EBITDA 5.3x, 6.4% yield, multi-metric undervaluation — classic Klarman cigar butt with margin of safety | China property crisis deepens |
| Catalyst-Driven (Tepper) | LONG MP, ALB | China export control expiry Nov 2026 is a binary catalyst; IRA credits starting to flow; lithium price inflection | Controls ease = premium unwinds |
| Macro Tactical (Druckenmiller) | LONG copper (FCX, TECK) | Structural copper deficit + AI data center demand + electrification = multi-year commodity supercycle | Global recession destroys demand |
Variant View
Market consensus: Critical minerals are a “nice story” but commodity prices are cyclical, Chinese oversupply will return, and these stocks are too volatile for core portfolios.
What the market is missing: This is not a commodity cycle — it is an industrial policy regime change. Five structural shifts are occurring simultaneously and each one alone would be bullish:
- China weaponized minerals — export controls on rare earths, gallium, germanium prove supply chain concentration is a geopolitical weapon, not just a risk factor
- Permitting timelines create structural scarcity — 7-10 year mine development means today’s deficit cannot be solved until the 2030s regardless of price signals
- IRA/Section 45X creates a two-tier market — domestically and ally-sourced minerals command a structural premium over Chinese-processed alternatives
- AI data centers are a new demand vector — copper demand from hyperscaler buildout is not in legacy mining company forecasts or analyst models
- Defense demand is inelastic — the Pentagon will pay whatever it costs for rare earth magnets for F-35s and precision-guided munitions. The 920 lbs of rare earths per fighter jet is non-negotiable
The consensus treats these stocks as cyclical commodity plays deserving 8-15x P/E multiples. The correct framework is to treat the reshoring beneficiaries (MP, FCX, TECK, LAC) as structural growth stories with government subsidy support — closer to defense contractors than traditional miners.
Pre-Mortem: Three Ways This Goes Wrong
-
China lifts export controls and floods the market. The November 2026 suspension expiry passes without renewal. Chinese rare earth processors resume full exports, rare earth prices collapse 40-50%, and MP Materials’ strategic premium evaporates. Lithium oversupply from Argentine and Australian projects depresses ALB earnings further. Copper falls below $10,000/mt on weakening Chinese construction. The entire reshoring thesis loses urgency. Portfolio drawdown: 25-35%.
-
Permitting and execution failure. Thacker Pass (LAC) hits construction delays and cost overruns — the $2.27B Phase 1 capex balloons. MP Materials’ Fort Worth magnetics plant fails to achieve commercial-scale NdFeB magnet production. Resolution Copper (BHP/RIO) remains stuck in environmental review indefinitely. PLL’s Carolina Lithium faces local opposition. Investors realize reshoring is a decade-long grind, not a near-term catalyst. Speculative names (MP, LAC, PLL) give back 40-60%.
-
Global recession destroys demand. A hard landing in China + European recession + US slowdown tanks industrial metals across the board. Copper falls to $8,000/mt, lithium resumes its 2023-2024 decline, iron ore breaks below $80/mt. Even the highest-quality miners (BHP, RIO) see 20-30% drawdowns. ALB’s Z-Score breach into distress becomes a solvency concern. The “structural demand” thesis is correct long-term but irrelevant to a portfolio that needs to survive the next 12 months.
Monitoring Dashboard
| Signal | What to Watch | Bullish Trigger | Bearish Trigger |
|---|---|---|---|
| China Export Controls | November 2026 suspension expiry | Controls extended or expanded | Controls lifted, full exports resume |
| Rare Earth Prices | NdPr oxide, dysprosium oxide spot | NdPr sustained above $100/kg | NdPr below $60/kg |
| Copper Price | LME copper spot | Sustained above $12,000/mt | Below $9,000/mt |
| Lithium Price | Lithium carbonate (China spot) | Recovery above $15,000/t | New lows below $8,000/t |
| IRA Implementation | Section 45X credit disbursements | Credits flowing to domestic producers | Program defunded or delayed |
| MP Magnetics | Quarterly updates on Fort Worth | Commercial NdFeB magnet shipments | Further delays, losses widen |
| Thacker Pass | LAC construction milestones | On-time, on-budget progress | Cost overruns, timeline slippage |
| Resolution Copper | BHP/RIO permitting updates | Final EIS approved | Blocked or indefinitely delayed |
| Pentagon Spending | DoD critical minerals budget | New contracts, DPA Title III orders | DOGE-style cuts to mineral programs |
| DRC Cobalt | Export ban status | Ban extended, supply tightens | Ban lifted, cobalt floods market |
Decision Framework
| Stock | Buy | Add | Reduce | Stop |
|---|---|---|---|---|
| RIO | $72 | $78 | $95 | $62 |
| FCX | $44 | $48 | $62 | $38 |
| TECK | $38 | $42 | $55 | $32 |
| VALE | $11 | $13 | $17 | $9 |
| ALB | $120 | $140 | $185 | $100 |
| BHP | $52 | $58 | $72 | $45 |
| MP | $38 | $45 | $70 | $30 |
| LAC | $2.50 | $3.20 | $5.50 | $2.00 |
Part 5 of “The Geopolitical Edge” series. Previous installments: Part 1: LNG Value Chain | Part 2: Defense & Munitions | Part 3: Photonics & Optical Networking available on the blog.
Disclaimer: Research and educational purposes only. Not investment advice. Data as of March 22, 2026. ALTM (Arcadium Lithium) is being acquired by Rio Tinto — shares trade as merger arbitrage, not a fundamental investment. LTHM (Livent) is delisted and merged into ALTM.