May 1, 2026
$AAPL Q2 FY2026 Deep Dive: Cook Hands the Baton, iPhone Supercycle, China +28% — Apple Hits Records Without the AI Capex Card
Apple Q2 FY2026: clean beat across the board — revenue $111.2B (+17%), iPhone $57B (+22%), Greater China +28%, gross margin 49.3% record, $100B additional buyback. Sept 1 transition: Cook → Ternus, biggest leadership change in 15 years. While the four mega-caps burn $700B on AI capex, Apple just showed you can hit all-time-high records without playing that card.
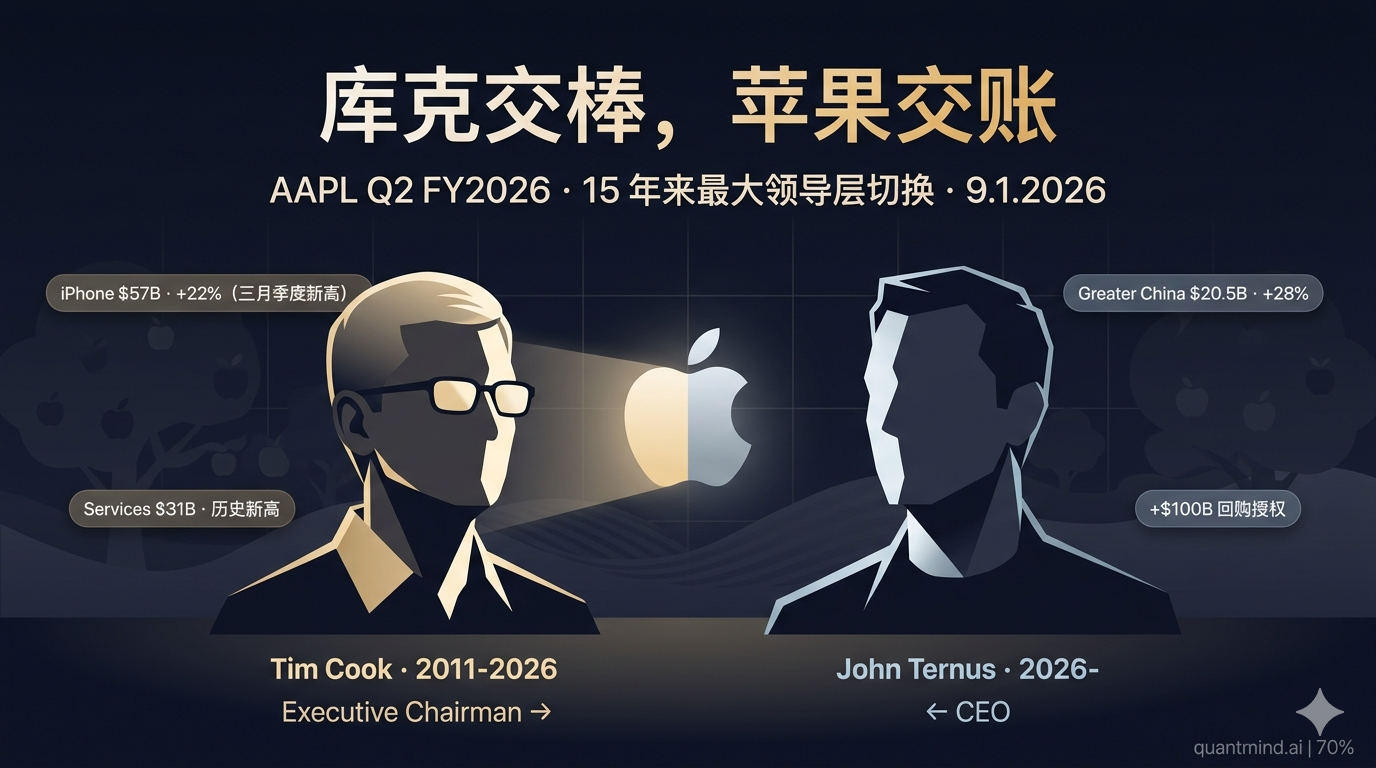
$AAPL Q2 FY2026 Deep Dive
Cook Hands the Baton, iPhone Supercycle, China Rebound — A Lesson for the AI-Capex Crowd
A Scene First
Last night GOOGL/MSFT/AMZN/META were still shouting $700 billion in AI capex. Today at 4:30 PM ET Apple walked out and said: “This quarter we spent $11.4B on R&D, did $111.2B in revenue, expanded gross margin to 49.3%, and authorized another $100B in buybacks.”
Then the stock went +4% after-hours.
This is not an AI story. It’s a story about what a real cash machine looks like.
And — Tim Cook hands the CEO baton to John Ternus on September 1. This is the biggest leadership transition Apple has had in 15 years, since Steve Jobs → Tim Cook in 2011. The market answered with +4% AH: no panic on the handoff, in fact reading it as “seamless succession.”
TL;DR
AAPL Q2 revenue $111.2B (+17% YoY), EPS $2.01 (+22%), iPhone $57B (+22% — March-quarter all-time high), Greater China $20.5B (+28%), gross margin 49.3% (record), additional $100B buyback authorization, +4% after-hours.
| Dimension | Verdict |
|---|---|
| Fundamentals | Clean beat across the board: iPhone, Mac, iPad, Services, gross margin, China — all above consensus |
| Position call | Long (core) — but priced in short-term, wait for pullback |
| Biggest variable | CEO transition (Sept 1, 2026) + tariffs + Apple Intelligence rollout pace |
| Action Price | $245 (first tranche, 12% margin), $225 (add, 20%), $200 (heavy, 30%) |
If you only remember one line: “Last night four megacaps bet $700B on AI capex; today Apple answered with $100B in buybacks. Same money — whose capital allocation do you trust?”
Key Forces
Force 1: iPhone 17 Supercycle + Greater China +28% Comeback
On the call, Cook explicitly called the iPhone 17 family “the most popular product lineup in Apple’s history since launch.”
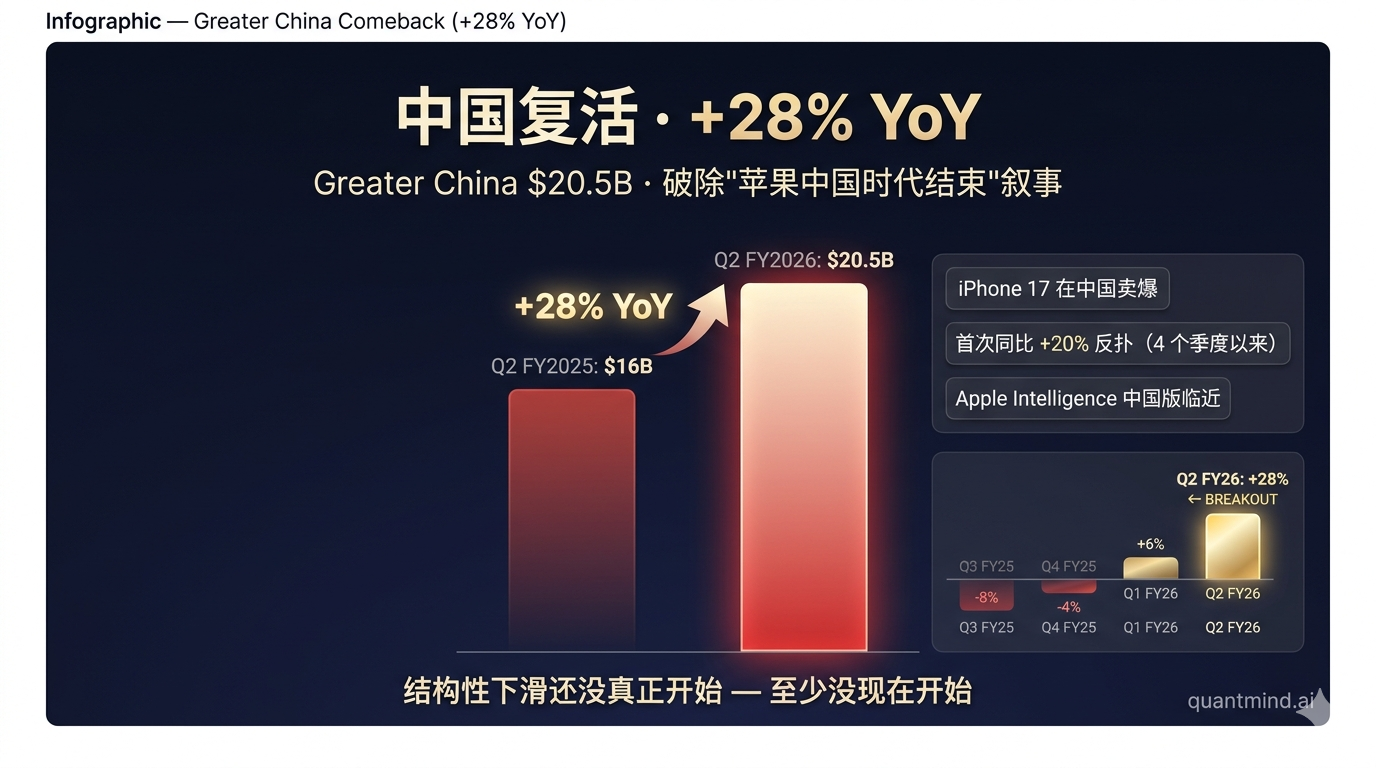
The data confirms it: - iPhone revenue $56.99B (+21.7% YoY) — highest March-quarter ever - Greater China revenue $20.5B (+28% YoY) vs $16B prior year - This is Apple’s first +20%+ YoY rebound in China under the Huawei/Xiaomi/OPPO siege
Translation: Through 2024-2025 the market kept saying “Apple’s China era is over.” This quarter says — the structural decline hasn’t really started, or at least not now. The combination of iPhone 17 + the upcoming China-localized Apple Intelligence is more effective than the bears modeled.
Force 2: CEO Transition = 15-Year Discontinuity
On September 1, Tim Cook becomes Executive Chairman; John Ternus takes the CEO chair.
This is Apple’s biggest leadership transition since Jobs → Cook in August 2011. Ternus’s profile:
- Currently SVP, Hardware Engineering
- Architect of the Apple Silicon transition (M-series chips) — the most consequential hardware project in Apple’s history
- Final authority on iPhone, iPad, Mac product lines
- Industry view: “Apple’s Sundar Pichai” — low-key, deeply technical, ferocious executor
Why this matters: - Cook era (2011-2026): turned Apple from “Steve Jobs’s company” into a $4 trillion-dollar global cash machine. - Ternus era (2026-?): faces a different exam — how does Apple’s “integrated stack” stay competitive in the AI era? Does it have to spend cloud capex?
The +4% AH reaction tells you the market isn’t worried short-term — Ternus isn’t a parachute hire, he’s the father of Apple Silicon. Medium- to long-term discontinuity risk is probably underpriced.
Force 3: The Anti-AI-Capex Trade
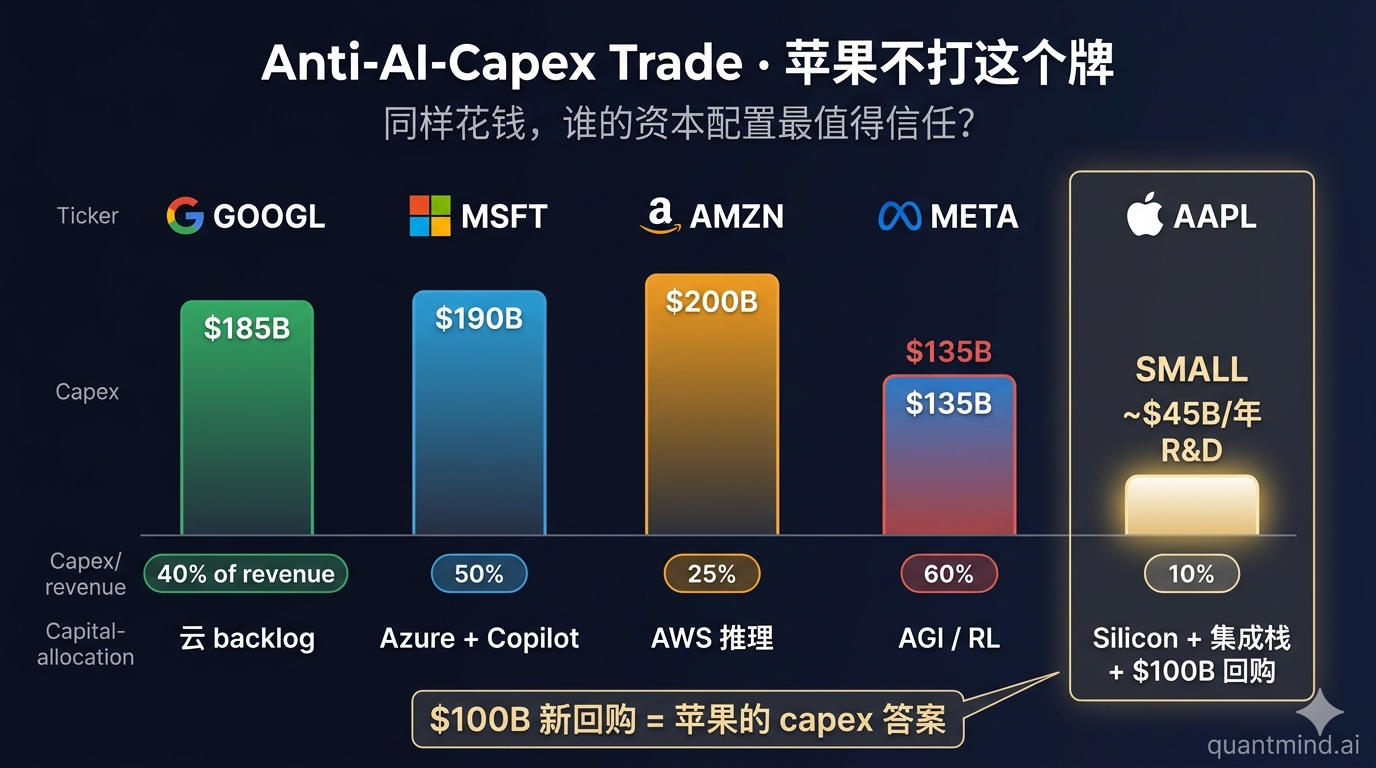
Place AAPL alongside last night’s GOOGL/MSFT/AMZN/META capex battlefield:
| Company | 2026 Capex Intensity | Capital Allocation Choice |
|---|---|---|
| GOOGL | $180-190B (~40% of revenue) | Bet on GCP backlog conversion |
| MSFT | ~$190B (~50%) | Bet on Azure + Copilot penetration |
| AMZN | ~$200B (~25%) | Bet on AWS leading the inference era |
| META | $125-145B (~60%) | Bet on AGI / Reality Labs |
| AAPL | ~$11.4B/quarter R&D (~10% of revenue) + $100B buyback | No capex bonanza — let Apple Silicon + integrated stack carry AI naturally |
Apple’s bet: While cloud players need to spend $700B to serve AI workloads, Apple runs on-device AI on 3 billion+ active devices (Apple Intelligence + M-series silicon + Neural Engine). If on-device AI’s energy-efficiency advantage cashes out via Vision Pro 2 / iPhone 18 / M5 Macs, AAPL is the only mega-cap that can ride the AI wave without spending capex.
The risk: If “on-device AI” is just a narrative, and consumers actually want cloud-side LLMs — AAPL becomes “iPhone-as-a-cloud-client,” and the hardware premium erodes.
Headline Numbers
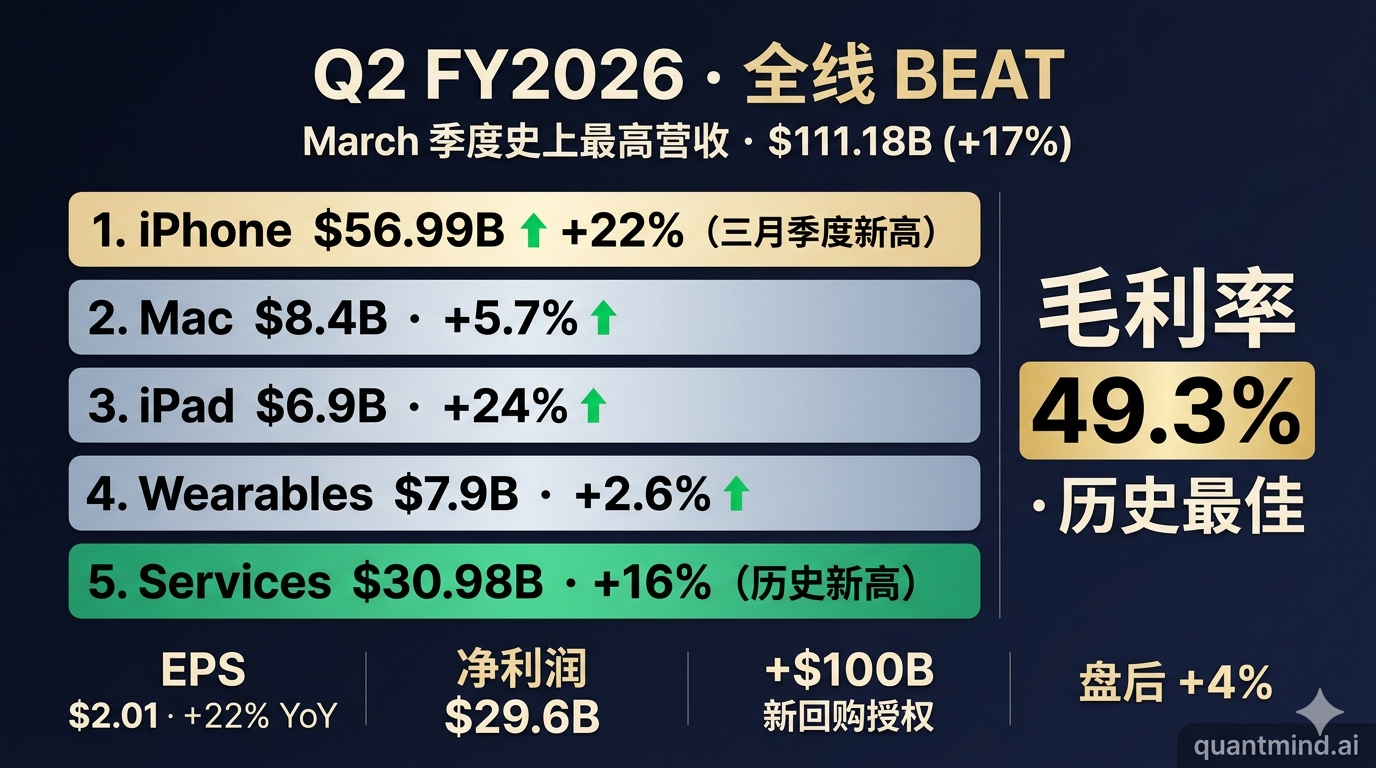
| Metric | Q2 FY2026 | YoY | Consensus | Beat/Miss |
|---|---|---|---|---|
| Revenue | $111.18B | +17% | $109.66B | ✅ +$1.52B |
| EPS (GAAP) | $2.01 | +22% | $1.95 | ✅ +$0.06 |
| Gross margin | 49.3% | +1.1pp | 48.4% | ✅ +0.9pp |
| iPhone | $56.99B | +22% | $56.5B | ✅ |
| Mac | $8.4B | +5.7% | — | ✅ |
| iPad | $6.9B | +24% | — | ✅ big beat |
| Wearables / Home | $7.9B | +2.6% | $7.7B | ✅ |
| Services | $30.98B | +16% | $30.39B | ✅ all-time high |
| Greater China | $20.5B | +28% | — | ✅ above expectations |
| Net income | $29.6B | +21% | — | ✅ |
| R&D | $11.42B | +33% | — | sharp acceleration |
| New buyback authorization | +$100B | — | — | ✅ |
| Dividend | $0.27 (+4%) | — | — | ✅ |
Note R&D +33%: This is the fastest YoY R&D growth in recent years — clearly stepping up Apple Intelligence, Vision Pro 2, and silicon investment. But even at +33%, R&D is only ~10% of revenue (vs GOOGL ~14%, META ~26%). Apple is investing in AI its own way: hardware + integrated stack, not data centers.
Valuation Matrix
Multi-method valuation
| Method | Estimate | Note |
|---|---|---|
| Forward P/E | ~31x (FY26E EPS ~$8.5) | Upper end of historical range |
| EV/EBITDA | ~21x | Above 5-year average (17x) |
| DCF | $250-280 range | 5% terminal growth |
| Shareholder yield | $100B buyback + $15B dividend ≈ ~3% of mkt cap | Still the world’s strongest cash-return engine |
Probability-weighted scenarios
| Case | Prob | 12M target | Return | Key assumption |
|---|---|---|---|---|
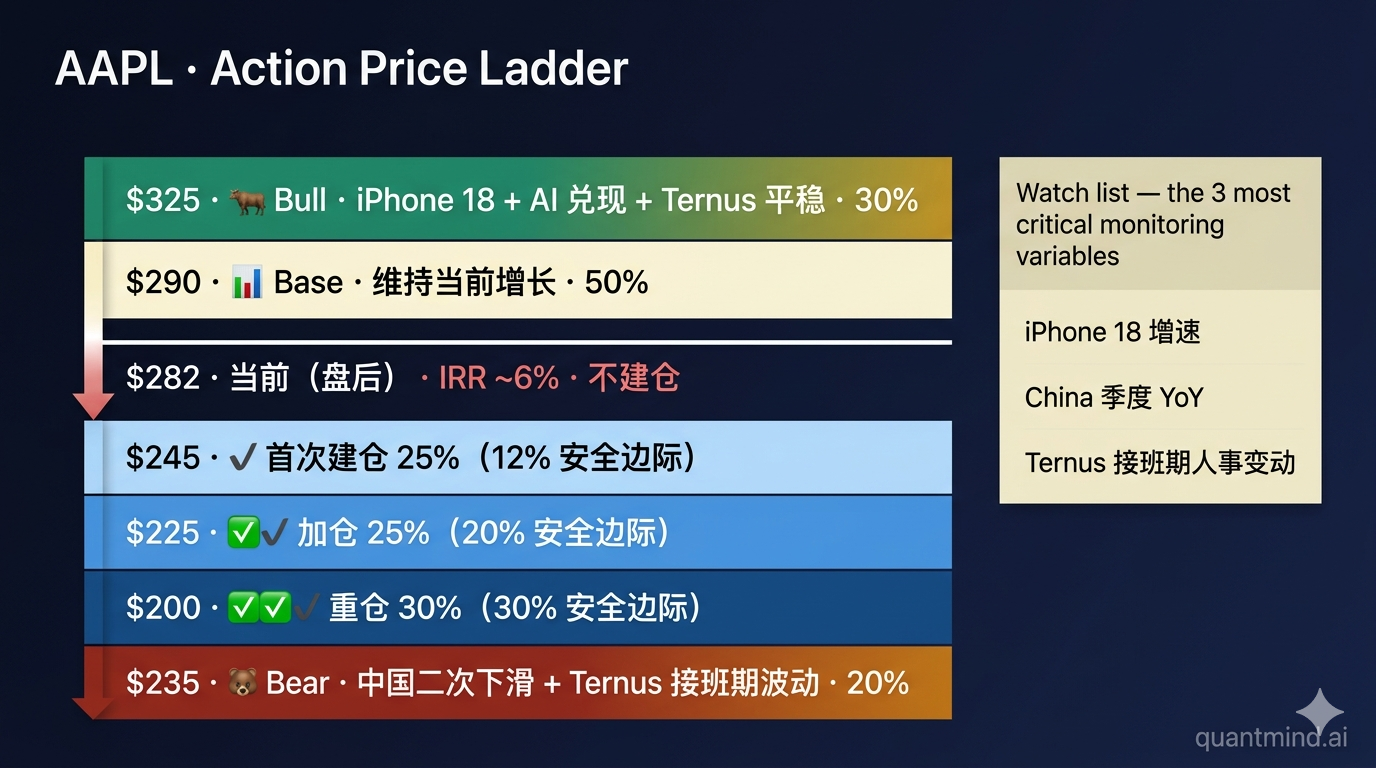
| 🐂 Bull | 30% | $325 | +20% | iPhone 18 + Apple Intelligence China rollout + smooth Ternus succession |
| 📊 Base | 50% | $290 | +7% | Maintain current trajectory, gross margin holds 49% |
| 🐻 Bear | 20% | $235 | -13% | China re-accelerates downward + tariff escalation + transition turbulence |
Probability-weighted target: $285 | Implied IRR: ~6%
IRR below 15% hurdle → current ~$282 (AH) does not trigger entry Wait for $245-260 zone, providing 12-15% safety margin
Action Price (valuation-driven, not feel-driven)
- First tranche: $245 (12% safety margin)
- Add: $225 (20% safety margin)
- Heavy: $200 (30% safety margin, historical mean P/E)
Variant View
Market consensus: Apple is an AI-era loser — no cloud, no LLM, slow Apple Intelligence rollout.
My view: The market is measuring Apple on the wrong AI battlefield.
Cloud players compete on “training + inference compute” — Apple doesn’t fight that war. Apple competes on “on-device AI experience across 3B active devices + services stickiness + China/India hardware share” — and on this battlefield, AAPL is still widening the moat.
Evidence: - iPhone 17 +22% YoY, March-quarter record - China +28% YoY, breaks the “China era over” narrative - Services $31B (+16%), subscription compounding still healthy - Gross margin 49.3% — still the highest in tech - $100B new buyback authorization — that’s “we have so much cash we don’t know what to do” signaling
Why the market was wrong before: In 2024-2025 markets equated “AI dividend = cloud capex dividend,” underweighting the monetization path of “on-device AI + integrated stack.” This quarter’s data starts correcting that bias.
Falsification points: - iPhone 18 (fall 2026) YoY < +5% → supercycle is over → flip short - Greater China YoY back to negative → structural decline confirmed → flip short - Apple Intelligence still can’t ship in EU/China → on-device AI narrative breaks
6 Investing Lenses
| Lens | Verdict | Reason |
|---|---|---|
| 🏦 Quality Compounders (Buffett) | Long | Buffett still a top holder; cash machine + user lock-in fits “wide moat + long compound” |
| 🚀 Imagination Growth (Baillie Gifford) | Neutral | Not an “imagination story,” a “compounder story” — better fit for Buffett style |
| 📈 Long/Short Fundamental (Tiger) | Long, wait for pullback | 31x forward is rich; 26x ($245) triggers entry |
| 💎 Deep Value (Klarman) | PASS (rich) | Private buyer estimate $230-250, no margin of safety |
| ⚡ Catalyst (Tepper/Ackman) | Long | iPhone 18 (fall) + Vision Pro 2 + Ternus transition = multi-catalyst window |
| 🌍 Macro Tactical (Druckenmiller) | Neutral-positive | Strong USD hurts (70%+ international revenue), but China rebound offsets |
Pre-Mortem: If This Is Badly Wrong in 2 Years
Path A (30%): iPhone 17 was a “fake supercycle” — just iPhone 14/15 replacement-cycle expiry. iPhone 18 (fall 2026) growth slows sharply → market re-rates AAPL back to “mature hardware company” → P/E compresses to 22x → $200 or below.
Path B (25%): Ternus succession execution problems — wavering AI strategy, slower product cadence, key talent departures → market loses faith in “post-Cook era” → multiple compresses materially.
Path C (20%): US-China tariff escalation reaches Apple’s products + India production capacity inadequate → gross margin compresses from 49% to 44% → meaningful EPS revision.
Path D (15%): Apple Intelligence stays blocked in China/EU regulatory regimes long-term → key selling point can’t ship → iPhone upgrade cycle disrupted.
Path E (10%): Unexpected macro event (recession + geopolitical conflict) → consumer electronics demand collapses broadly.
Action Triggers
| Signal | Action | Size |
|---|---|---|
| Pulls back to $245 | First tranche | 25% |
| Pulls back to $225 | Add | +25% |
| Pulls back to $200 (fundamentals intact) | Heavy | +30% |
| iPhone 18 launch YoY ≥ +10% | Add | +15% |
| Greater China ≥ +20% YoY for 2 consecutive quarters | Maintain / add | — |
| Gross margin < 47% for 2 consecutive quarters | Trim | -30% |
| Greater China YoY < 0% in any quarter | Trim | -30% |
| 3+ key executives leave within 6 months of Ternus succession | Trim | -20% |
| iPhone 18 YoY < 0% (decline) | Cut | 100% |
Watch List (Next 4 Quarters)
- iPhone 18 launch data (fall 2026): YoY growth, week-1 activations, China pre-orders.
- Greater China quarterly revenue: Can it hold +15%+?
- Services growth: Can it hold +15%+? Will App Store antitrust rulings impact it?
- Gross margin: Can it stay above 49%? Tariffs + India capacity transition are key.
- R&D growth rate: Sustained +25%+ = Apple investing aggressively in AI.
- Vision Pro 2 / new hardware categories: Can any become a $10B+ business?
- Ternus-era personnel changes: Retention of core executives (Tim Millet, Johny Srouji, Eddy Cue).
- India vs China production mix: Apple’s geopolitical hedging progress.
Conclusion
AAPL just gave the AI-capex theater a lesson: without playing the $700B card, you can still print all-time-high revenue, +$100B buybacks, and 49.3% gross margin.
The next exam is September 1: whether the Ternus era can deliver “on-device AI + integrated stack” through iPhone 18 / Vision Pro 2.
Operationally: - At ~$282 (AH) the IRR doesn’t clear → wait - Pull back to $245 → first tranche 25% position - Pull back to $225 → add to 50% position - Treat AAPL as “the tech ballast” — not your alpha source, your beta stabilizer
Contrast with last night’s mega-cap quartet: - Same money, AAPL chooses $100B buybacks + on-device AI - Same “AI exposure,” AAPL doesn’t tell a capex story but ships through a real distribution channel of 3B+ devices
If you bought GOOGL last night, do you buy AAPL today? Not mutually exclusive — different time-horizons: - GOOGL is a 1-3 year bet on “capex-conversion proof” - AAPL is a 5-10 year bet on “integrated-stack durability”
Closing Thought
The two data points that hit me hardest:
- iPhone in China +28% YoY — through a year of “Apple’s China is dead” pieces, Q2 delivered the strongest rebound in four quarters.
- R&D +33% YoY but no capex blowout — Apple is investing in AI its own way without dragging itself into the $700B arms race.
Cook’s last full quarter as CEO gave the market a lesson: not every AI dividend requires capex to capture.
For the next 5 months, everyone watches Sept 1 — Ternus’s first move. I’ll watch two specifics: - The fall keynote: can Apple Intelligence ship in China? - iPhone 18 cadence: does it carry any “Ternus fingerprint”?
If those two surprise positively, AAPL’s valuation ceiling opens up. If not, $245 is the rational level.
Analysis based on Apple Q2 FY2026 earnings reported April 30, 2026 post-market. Sources: Apple Newsroom, CNBC, Motley Fool earnings call transcript, AppleInsider, 9to5Mac, Bloomberg. ⚠️ Not investment advice. For research purposes only.